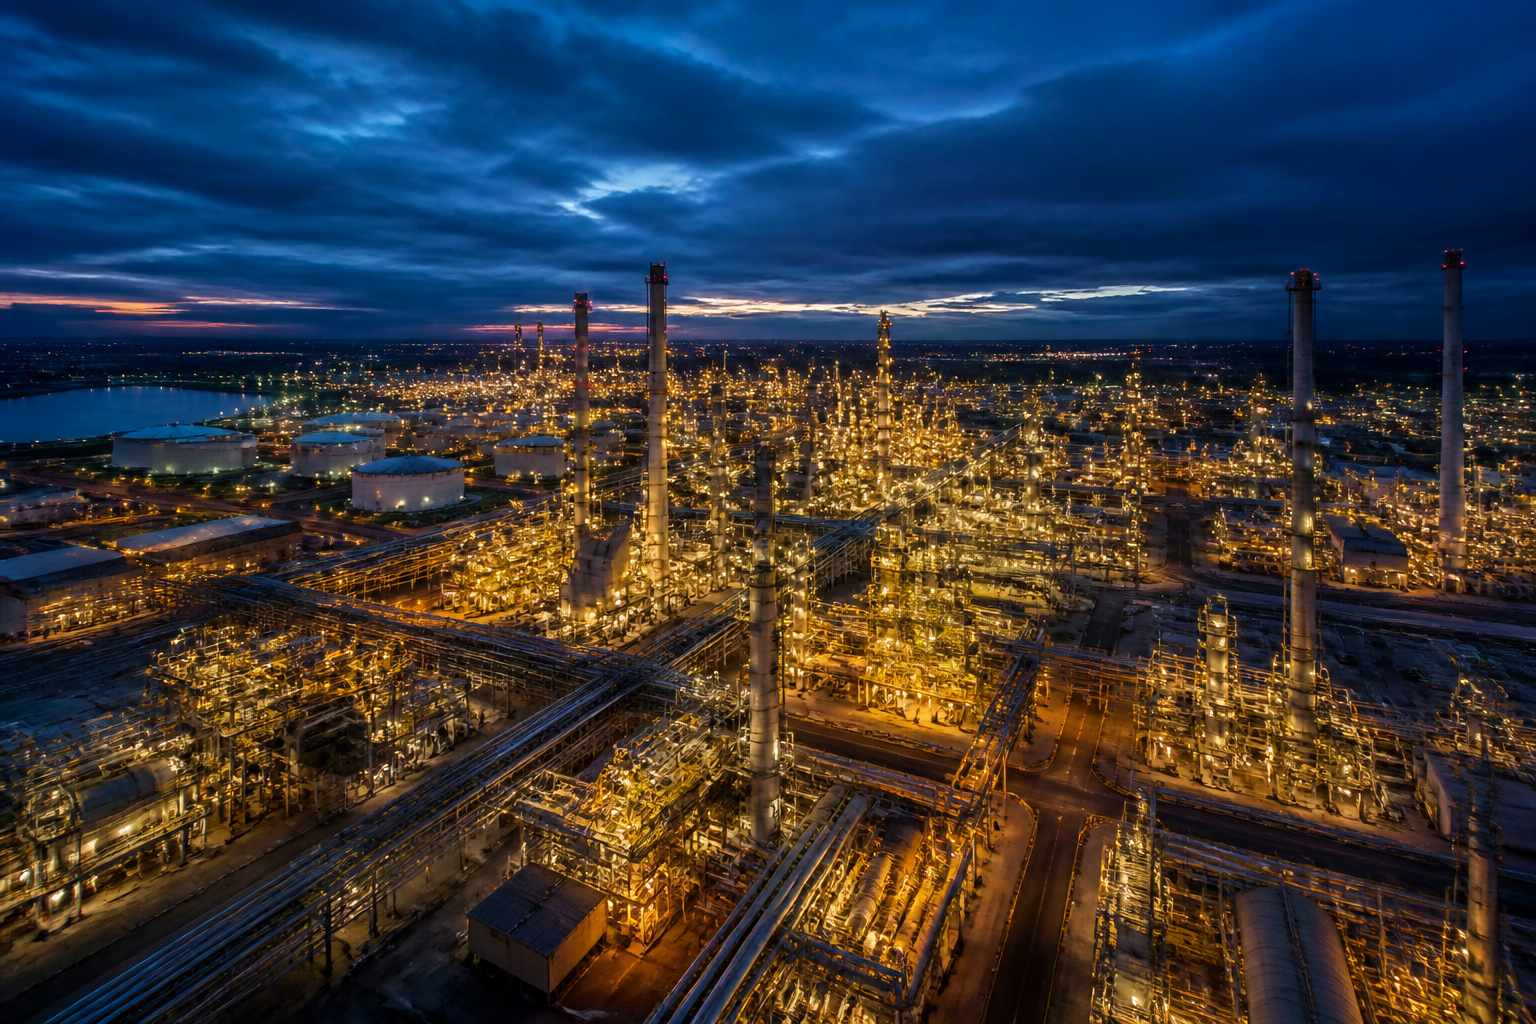
The Refinement Trap: How Divergent Energy Prices Challenge Global Monetary Stability
This editorial analyses the growing rift between crude oil benchmarks and the cost of refined fuels, examining how this persistent premium complicates the mandate of central banks to maintain price stability.
The global energy landscape is currently defined by a paradox that threatens to undermine the fragile equilibrium sought by central bankers from Washington to Frankfurt. Whilst crude oil benchmarks have historically served as the primary barometer for inflationary expectations, a significant decoupling has emerged. The persistent elevation of refined energy product prices relative to their underlying crude components indicates a systemic bottleneck in the global industrial complex. This divergence, characterised by widening crack spreads and tightening distillate supplies, suggests that the cost of energy for the end consumer is no longer merely a function of extraction, but rather a reflection of a fractured and insufficient refining infrastructure. As Treasury yields in the United States hover near multi-year highs and European markets suffer through consecutive periods of contraction, the spectre of a second inflationary strike looms, driven not by the scarcity of raw materials but by the technical and geopolitical constraints of processing them.
The Widening Gulf Between Crude and Product
Recent data from Deloitte Insights underscores a troubling trend where refined energy products maintain a significant price premium over crude oil. This phenomenon is not merely a temporary market inefficiency but rather the result of a decade of under-investment in downstream capacity across Western economies. The price of diesel and jet fuel, which act as the lifeblood of global logistics and commerce, has remained stubbornly high even during periods of relative stability in Brent or West Texas Intermediate benchmarks. This persistent cost pressure creates a floor for core inflation that monetary policy is ill-equipped to address. Central banks typically respond to demand-pull inflation by raising interest rates, yet these tools have limited efficacy against supply-side constraints within the refining sector. The industrial reality is that many older refineries have been decommissioned or converted to biofuels, leaving the global market vulnerable to even minor disruptions in the remaining facilities. Consequently, the cost of moving goods and people remains elevated, exerting a continuous upward pressure on the Producer Price Index, as evidenced by recent data from Finland showing year-on-year increases in import and export prices reaching beyond seven per cent.
Monetary Policy and the Second Strike of Inflation
Economists are increasingly concerned about what is described as the second strike of oil on inflation. The initial shock following geopolitical realignments led to a sharp spike in headline figures, but the current phase is more insidious. It involves the embedding of higher energy costs into the broader service and manufacturing sectors. When energy prices remain elevated for a prolonged period, businesses are forced to pass these costs to consumers to preserve their margins. This transition from transitory energy volatility to structural price increases is precisely what the Federal Reserve and the European Central Bank fear. The recent surge in Treasury yields reflects a market that is beginning to price in a higher-for-longer interest rate environment, necessitated by the failure of energy prices to return to their pre-crisis norms. As Greg Ip of the Wall Street Journal has noted, the risk of a secondary inflationary impulse is growing, particularly as the base effects of previous year comparisons begin to fade. This leaves little room for the accommodative policy that equity markets have been anticipating, leading to the sustained losses observed in recent trading sessions.
The Geopolitical Dimension of Refining Capacity
Refining capacity has become a new front in the struggle for economic sovereignty. While North American markets have benefited from a relatively integrated energy infrastructure, the European continent remains precarious. The reliance on imported refined products has created a dependency that is susceptible to both political volatility and logistical failures. The alliance between Canada and Europe, while promising for long-term energy security, faces immediate hurdles in the form of political opposition and the sheer scale of the required capital expenditure. In Asia, the budget balances of nations like the Philippines are being strained by the need to subsidise energy costs to prevent domestic unrest, illustrating the painful economic trade-offs that leaders must navigate. The shift in global refining power towards the Middle East and China has further complicated the situation, as Western nations find themselves dependent on finished products from regions that may not share their strategic or economic priorities. This geographical mismatch between where crude is extracted and where it is refined adds layers of cost and risk to the global supply chain, ensuring that energy remains a volatile component of the macroeconomic outlook.
Fiscal Strain and the Sovereign Debt Conundrum
The interaction between energy prices and sovereign debt is becoming increasingly critical. As governments are forced to choose between allowing energy costs to destroy consumer purchasing power or intervening with costly subsidies, their fiscal positions deteriorate. In the United Kingdom and the Eurozone, the cost of servicing debt is rising alongside the cost of energy, creating a twin challenge for finance ministries. The recent economic calendar highlights significant budget deficits in emerging markets that are exacerbated by energy imports. High energy prices act as a regressive tax on the economy, reducing the disposable income of households and the profitability of energy-intensive industries. This reduces the tax base at the same time that the cost of government borrowing is increasing due to the inflationary environment. The result is a narrowing of the fiscal space available for investment in transition technologies or social infrastructure. The bond market, sensitive to these shifts, has responded by pushing yields higher, which in turn increases the cost of capital for the very energy projects required to solve the capacity crisis.
The Logistics of a Fragmented Market
Logistics and transport sectors are the primary conduits through which refined product prices infect the broader economy. The cost of maritime shipping and trucking is highly sensitive to the price of middle distillates. As refining margins remain high, the cost of diesel remains a persistent burden for the logistics industry. This has a cascading effect on every sector that relies on the movement of goods, from agriculture to high-tech manufacturing. The resilience of these prices, despite attempts by central banks to cool the economy, suggests that the global supply chain is facing a structural shift rather than a cyclical fluctuation. The move towards just-in-case inventory management, as opposed to the pre-pandemic just-in-time model, requires more transport and storage, further increasing the demand for refined fuels. In this environment, the efficiency of the refining sector becomes a primary determinant of economic competitiveness. Regions that can secure stable and affordable access to refined products will have a significant advantage in the coming decade, while those dependent on volatile global markets will face continued economic headwinds.
Strategic Implications for Global Business
For the corporate sector, the current energy paradigm requires a fundamental reassessment of risk and cost structures. The assumption of cheap, readily available energy that underpinned the globalization of the last thirty years is no longer valid. Companies are now forced to integrate energy price volatility into their long-term strategic planning. This includes investing in energy efficiency, diversifying supply chains, and in some cases, reshoring production to regions with more stable energy costs. The role of artificial intelligence and advanced data analytics in optimizing energy consumption is becoming a critical tool for maintaining margins. However, these technological solutions cannot fully offset the fundamental mismatch between refining supply and global demand. The corporate landscape is likely to see a further divergence between winners and losers, based on their ability to navigate this high-cost energy environment. Institutional investors are increasingly looking at energy resilience as a key metric for evaluating sovereign and corporate debt, adding another layer of complexity to the global financial system.
Forward Looking Outlook
Looking toward the mid-term horizon, the global economy appears trapped in a cycle where energy constraints dictate the pace of growth. The transition to renewable energy, while necessary, does not provide an immediate solution to the refining bottleneck, as the current industrial infrastructure is still overwhelmingly dependent on liquid fuels. We expect that refining margins will remain historically elevated until significant new capacity comes online, primarily in non-Western jurisdictions. This will keep inflationary pressures high and prevent central banks from returning to a more accommodative stance. The risk of a recession remains significant, particularly in Europe and parts of Asia, as the trade-off between inflation control and economic growth becomes more painful. Policymakers must move beyond short-term subsidies and address the structural deficiencies in energy processing if they hope to restore long-term stability. The coming eighteen months will be a period of intense scrutiny for both monetary and fiscal authorities, as they attempt to navigate the treacherous waters of a second-strike inflationary environment without triggering a deeper systemic crisis.