The Scarcity Trap: Global Infrastructure and the Fragile Equilibrium of 2026
Economic & Actu examines the profound disconnect between record-high equity rallies and the deteriorating physical assets of the West, contrasted with the ambitious logistics transformation currently unfolding in Ethiopia.
The global economic landscape in August 2026 presents a paradox that challenges the fundamental tenets of classical fiscal theory. While the Dow Jones Industrial Average and the S&P 500 ascend to historic heights, propelled by a curious synthesis of lacklustre employment figures and the sudden prospect of a diplomatic thaw between Washington and Tehran, the underlying physical architecture remains in a state of precarious neglect. This disconnect suggests that the current equity rally is less a reflection of robust industrial health and more a symptom of a 'liquidity flight' into perceived safe havens, even as the essential conduits of trade, ports, power grids, and digital networks, suffer from chronic under-investment. The resilience of the consumer, as noted by Brian Moynihan of Bank of America, provides a temporary floor for economic sentiment, yet the structural integrity of the macroeconomy depends on a transition from speculative exuberance to tangible capital expenditure.
The Geopolitical Dividend and Logistics Reorientation
The recent surge in the Dow Jones, following reports of a potential peace treaty between the United States and Iran, highlights the extreme sensitivity of modern infrastructure to geopolitical volatility. Should a formal rapprochement occur, the immediate implication would be the reintegration of Iranian energy and shipping capacity into the global supply chain, potentially easing the inflationary pressures that have haunted the Eurozone and North America for years. However, the optimism of the markets must be tempered by the reality of the physical bottlenecks that persist in the Strait of Hormuz and the Suez Canal. For the infrastructure desk, the lesson of 2026 is that peace is not merely a diplomatic achievement but a logistical imperative. Without a stable security framework, the massive investments required for green hydrogen corridors and enhanced maritime security remain trapped in the boardrooms of multinational conglomerates, waiting for a signal of long-term stability that the current US administration is only now beginning to provide.
The Labour Paradox and Automation’s Infrastructure Toll
Recent data indicating a cooling US jobs market has, counter-intuitively, acted as a catalyst for stock market gains, as investors anticipate a more dovish stance from the Federal Reserve. Yet, this cooling masks a deeper structural shift in the labour-infrastructure nexus. As firms like Airtable face valuation collapses and the 'brain drain' of artificial intelligence talent shifts from established tech giants to nimble, decentralised startups, the demand for traditional office infrastructure continues to erode. The infrastructure of the future is increasingly energy-intensive rather than space-intensive. The rise of China-led AI data initiatives and the massive quarterly growth reported by SpaceX suggest that the next frontier of capital expenditure lies in low-earth orbit and hyper-scale data centres. The challenge for policymakers is that these high-tech assets do not provide the broad-based employment of the mid-20th-century public works projects, leading to the growing wealth disparity highlighted by social commentators regarding the bottom twenty per cent of the global population.
East African Aspirations: The Ethiopian Model
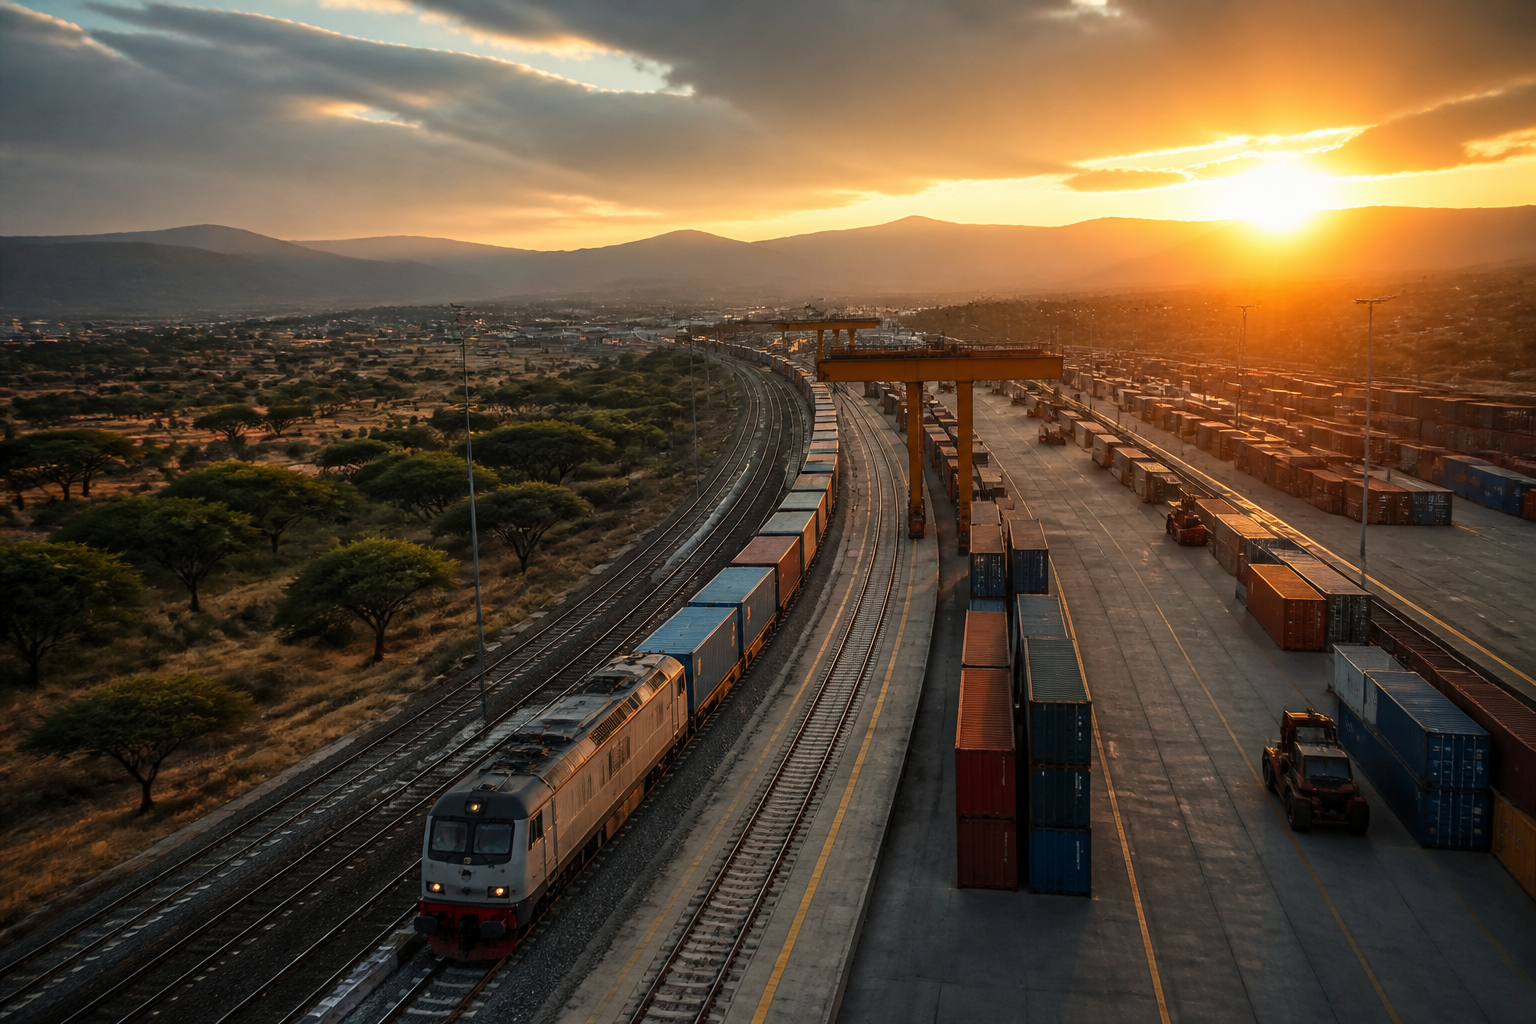
While the developed West grapples with the obsolescence of its legacy systems, Ethiopia has emerged as a vanguard of economic transformation through targeted logistical integration. The Ethiopian government’s strategy of 'Connecting Africa' serves as a blueprint for the Global South, leveraging its position as a regional aviation and manufacturing hub to bypass traditional stages of industrial development. By investing heavily in rail links to Djibouti and modernising its telecommunications backbone, Addis Ababa is not merely participating in trade; it is defining the terms of its engagement with the global market. This transformation proves that infrastructure is the ultimate multiplier; it is the difference between a nation remaining a commodity exporter and becoming a value-added service economy. The success of the Ethiopian model, however, remains contingent on the continued flow of foreign direct investment, which is currently being diverted by the high-interest-rate environment in the United States and the allure of high-yield AI ventures.
The Resiliency Gap in Developed Markets
Despite the 'healthy economic backdrop' cited by Bank of America’s leadership, the vulnerability of Western infrastructure to climate-driven shocks and cyber-warfare has never been more apparent. The resilience of the American consumer, who has thus far sustained the domestic economy through sheer spending power, is being tested by the rising costs of insurance and utility services, both of which are direct consequences of failing infrastructure. The S&P 500’s upcoming earnings tests will likely reveal a sharp divide between companies that have secured their supply chains through 'friend-shoring' and those still exposed to the fragilities of just-in-time logistics. For the institutional investor, the focus is shifting away from growth at any cost toward 'operational durability.' We are seeing a move toward decentralised micro-grids and private-public partnerships (PPPs) that aim to insulate critical services from the failings of the national grid, though these solutions risk creating a two-tier system where only the affluent have access to reliable power and water.
Space as the New Critical Domain
The stratospheric performance of SpaceX this quarter underscores a fundamental shift in what constitutes 'infrastructure.' No longer confined to the terrestrial realm, the logistics of the 21st century now encompass satellite constellations that provide the connectivity necessary for everything from automated agriculture to high-frequency trading. As SpaceX dominates the launch market, the commoditisation of orbit has become a strategic asset for the United States, providing a counterweight to China’s growing influence in terrestrial telecommunications. However, this reliance on private entities for public-good infrastructure raises significant questions regarding oversight and sovereignty. If the digital nervous system of a nation is owned by a single corporation, the traditional definitions of national security and public utility must be rewritten. The editorial position of this publication is that we are witnessing the birth of a 'celestial infrastructure' class, which will eventually demand the same level of regulatory scrutiny as the railways or the telephone networks of the previous century.
The Bottom Quintile and the Cost of Neglect
One cannot discuss the heights of the Dow Jones without addressing the stagnation of the bottom quintile of the income distribution. The failure of infrastructure to provide social mobility is the most damning indictment of the current economic cycle. When public transport systems fail, when affordable housing remains disconnected from employment hubs, and when digital literacy is hampered by poor rural broadband, the economy loses a significant portion of its productive potential. The 'resilient consumer' is a luxury of the middle and upper classes; for the bottom twenty per cent, the economic reality is one of diminishing returns and increasing isolation. Any infrastructure plan that focuses solely on the high-tech and the lucrative, while ignoring the basic circulatory systems of society, is doomed to generate the kind of populist volatility that ultimately undermines market stability.
A Forecast of Reintegration
Looking toward the final quarter of 2026, the global economy stands at a crossroads. The potential for a US-Iran peace deal offers a rare opportunity to recalibrate global energy markets and reinvest the 'peace dividend' into the deteriorating ports of the Mediterranean and the Persian Gulf. However, the path ahead is fraught with the risk of an 'infrastructure bubble,' where investment is poured into speculative technology at the expense of the physical foundations required to sustain it. The coming months will determine whether the current stock market rally is a harbinger of a new era of industrial renewal or merely a final flourish before a period of structural stagnation. For the discerning investor, the mandate is clear: prioritise assets that demonstrate tangible utility and geographical resilience. The age of the 'asset-light' economy is ending; the age of the 'infrastructure-heavy' recovery is about to begin.