The Structural Paradox: Reconciling Logistics Resilience With Global Capital Constraints
A deep dive into the diverging fortunes of global business structures. While refined energy prices squeeze industrial margins, strategic investments in port infrastructure and regional logistics hubs offer a path forward.
The global economic landscape is currently defined by a profound misalignment between the physical requirements of trade and the availability of capital for long-term business structures. As institutional investors, including BlackRock, pivot their attention toward emerging markets with a renewed sense of optimism, a shadow remains over the traditional engines of industrial growth. The primary friction point lies within the widening gap between crude oil benchmarks and the cost of refined energy products, a disparity that continues to erode the operational margins of heavy industry and logistics providers alike. While the broader macroeconomic discourse often focuses on headline inflation or interest rate trajectories, the more visceral challenge for the global economy is the persistent weakness in investment for physical structures. This reluctance to commit capital to the bricks and mortar of industry, despite the apparent resilience of consumer demand, suggests a structural hesitancy that could redefine the geography of production for the coming decade.
The Divergence of Refined Energy and Industrial Viability
Analyses from Deloitte Insights indicate a troubling trend where the prices of refined energy products remain stubbornly elevated even when crude oil prices show signs of moderation. This technical decoupling represents a significant hurdle for the infrastructure sector, particularly for those industries that rely on high-intensity thermal processes or massive freight movements. The cost of diesel and jet fuel, the lifeblood of global logistics, has not mirrored the periodic softenings in the Brent or WTI markets, creating a permanent inflationary floor for supply chain operations. This environment has effectively chilled the outlook for investment in new business structures, as the projected return on capital is frequently consumed by the volatility of energy inputs. The result is a landscape where existing facilities are pushed to their limits while the pipeline for new, more efficient industrial capacity remains dangerously thin, potentially leading to a supply side bottleneck as global trade volumes attempt to recover.
Maritime Hubs as Anchors of Regional Stability
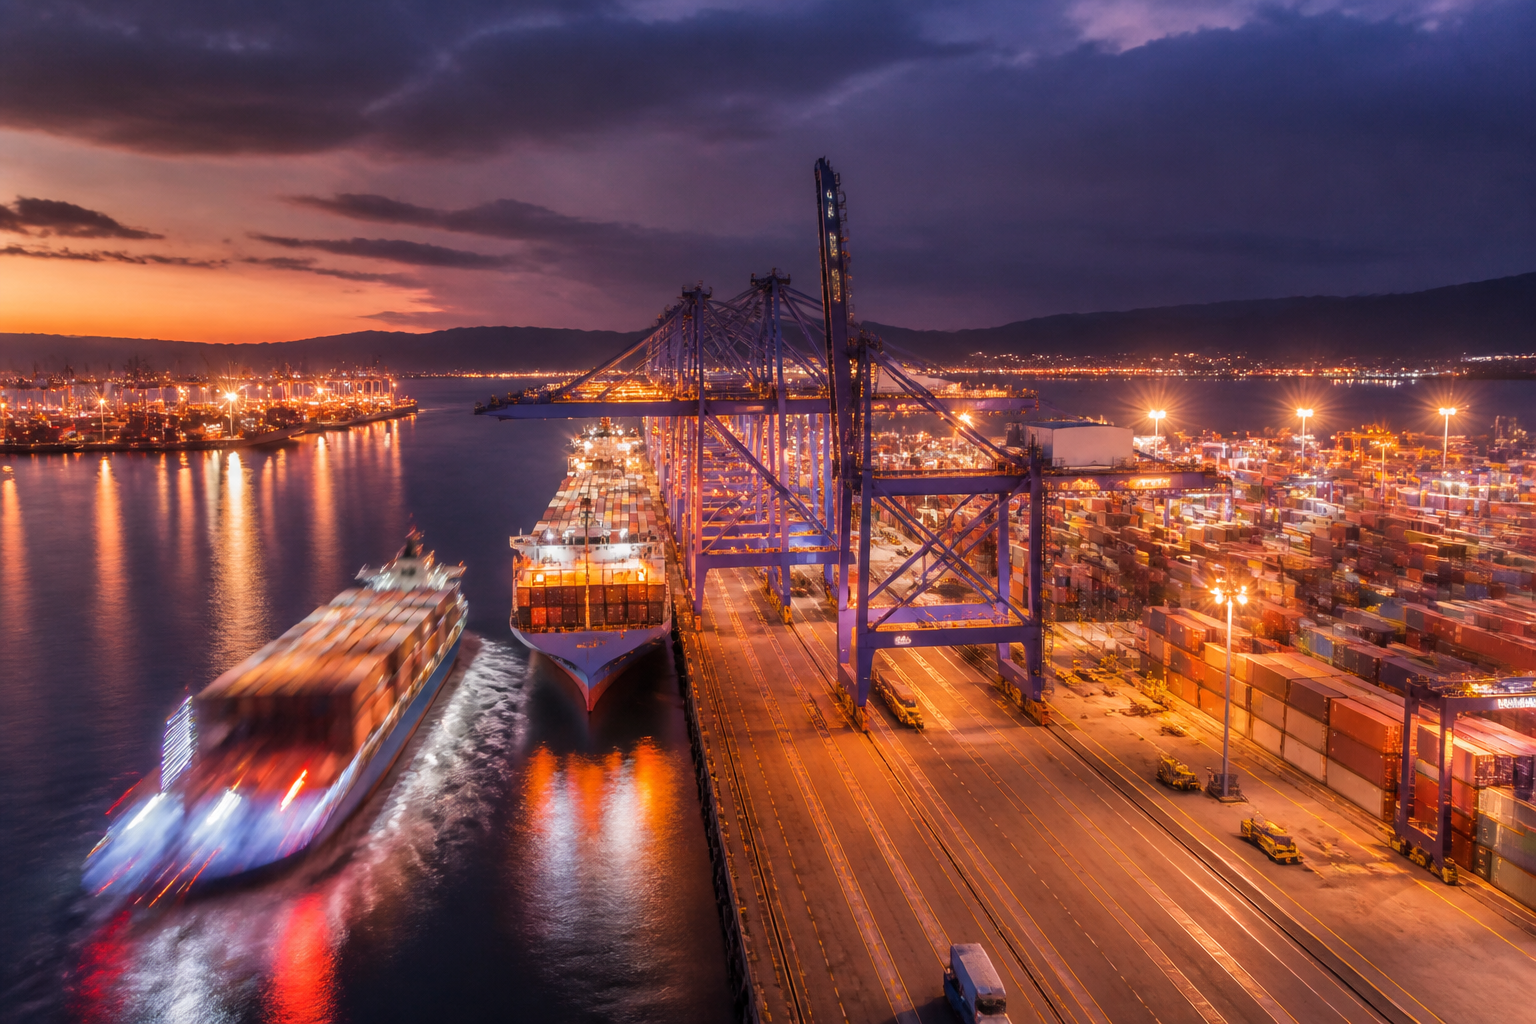
In contrast to the broader stagnation in business structures, strategic maritime assets are increasingly viewed as the primary stabilizers of regional economies. A pertinent example of this trend is observed in the activities surrounding the Port of Virginia, which has become a focal point for businesses from Botetourt County and the wider Appalachian region. These enterprises are seeking to insulate themselves from global volatility by strengthening their direct connections to major deep water terminals. The movement of state and regional leaders at Radford University to discuss these logistical synergies highlights a growing recognition that infrastructure is no longer a passive utility but a competitive weapon. By integrating local manufacturing bases more tightly with sophisticated port facilities, regions are attempting to bypass the inefficiencies inherent in fragmented global supply chains. This shift toward port-centric logistics reflects a broader global movement where proximity to efficient multimodal hubs is becoming the most critical factor in industrial site selection.
The Shift Toward Emerging Market Equities and Infrastructure
Recent movements by the BlackRock Investment Institute to upgrade emerging market equities to an overweight status signal a significant shift in the global risk appetite. This change in sentiment is driven by the belief that the valuation gap between developed and developing markets has become too wide to ignore, particularly as many emerging economies demonstrate superior fiscal discipline. However, this capital rotation has direct implications for infrastructure. For emerging markets to sustain this newfound investor interest, they must address the chronic underinvestment in their power grids and transport networks. The transition of capital from stagnant developed-market structures toward high-growth emerging-market infrastructure represents a rebalancing of the global portfolio. Investors are increasingly looking for opportunities where the marginal impact of a new road, bridge, or terminal is highest, which naturally leads them away from the saturated and high-cost environments of the West toward the expanding urban centres of the Global South.
Regionalism and the Rebirth of Domestic Supply Chains
As the costs of refined energy make long-distance shipping less predictable, the drive toward regionalization has accelerated. The recent economic development luncheons held in Virginia are indicative of a global pattern where local governments and private enterprises are forming tighter coalitions to secure their supply chains. This is not merely an exercise in protectionism, but rather a pragmatic response to the fragility of global networks exposed by recent geopolitical shocks. The focus is shifting toward the creation of self-sustaining industrial ecosystems that can operate with minimal reliance on intercontinental transit. For the infrastructure sector, this means a pivot from mega-projects designed for global trade toward mid-scale projects that enhance regional connectivity. Short-sea shipping, inland rail terminals, and regional warehouse clusters are receiving the attention that was once reserved for massive trans-shipment hubs, reflecting a more granular approach to economic resilience.
Private Markets and the Search for Yield in Hard Assets
S&P Global has identified a growing intersection between private markets and global trade infrastructure, as traditional public funding proves insufficient to meet modern demands. Private equity and sovereign wealth funds are increasingly stepping into the void left by cash-strapped governments, bringing a more rigorous, data-driven approach to infrastructure management. This influx of private capital is particularly visible in the digitalization of port operations and the expansion of automated logistics centres. However, the requirement for these investments to generate market-rate returns often clashes with the public-service nature of infrastructure. The challenge for the next several years will be to find a sustainable middle ground where private efficiency can be harnessed without compromising the accessibility of essential trade routes. The trend towards the privatization of logistics assets is likely to continue as long as interest rates remain relatively high, forcing operators to seek every possible efficiency through technological integration.
Future Outlook for Global Trade Infrastructure
Looking ahead, the global infrastructure landscape will likely be defined by a stark contrast between those regions that successfully integrate their logistics assets and those that remain mired in outdated structural models. The persistent elevation of refined energy prices will act as a permanent filter, favouring regions with high-density transport links and efficient energy management systems. We expect to see a continued migration of capital toward emerging markets, though this will be tempered by the need for those nations to prove their regulatory stability. The role of data and predictive analytics, as championed by firms like S&P Global, will become indispensable for navigating the complexities of modern trade. Ultimately, the successful infrastructure of the future will not be measured by its scale alone, but by its ability to provide a stable platform for commerce in an era of permanent energy volatility and shifting geopolitical alliances. The era of cheap, friction-less global trade has passed, and in its place, a more fragmented but potentially more resilient regional order is beginning to take shape.