The New Geopolitics of Crude: Strategic Tensions and the Resilience of Fossil Capital
Global energy markets are entering a period of heightened geopolitical risk as tensions in the Middle East and shifting policy towards Venezuela drive price volatility and institutional repositioning across the sector.
The global energy complex finds itself at a precarious crossroads, caught between the structural imperatives of the low-carbon transition and the immediate, visceral realities of geopolitical instability. Recent surges in crude prices, precipitated by escalating military friction in the Strait of Hormuz and a fundamental realignment of American diplomatic posture toward Venezuela, have injected a fresh dose of volatility into a sector that many analysts had previously predicted would remain stagnant. While the NYSE Energy Sector Index and the State Street Energy Select Sector SPDR Fund have demonstrated remarkable resilience, climbing significantly in recent sessions, the underlying drivers of this growth are increasingly rooted in systemic fragility rather than organic demand. The confluence of a more assertive Iranian naval presence and the potential for a transformative deal involving Chevron and the Venezuelan administration suggests that the age of fossil fuel dominance is not merely ending, but rather entering a more volatile, high-stakes final act.
The Hormuz Bottleneck and Regional Security Risks
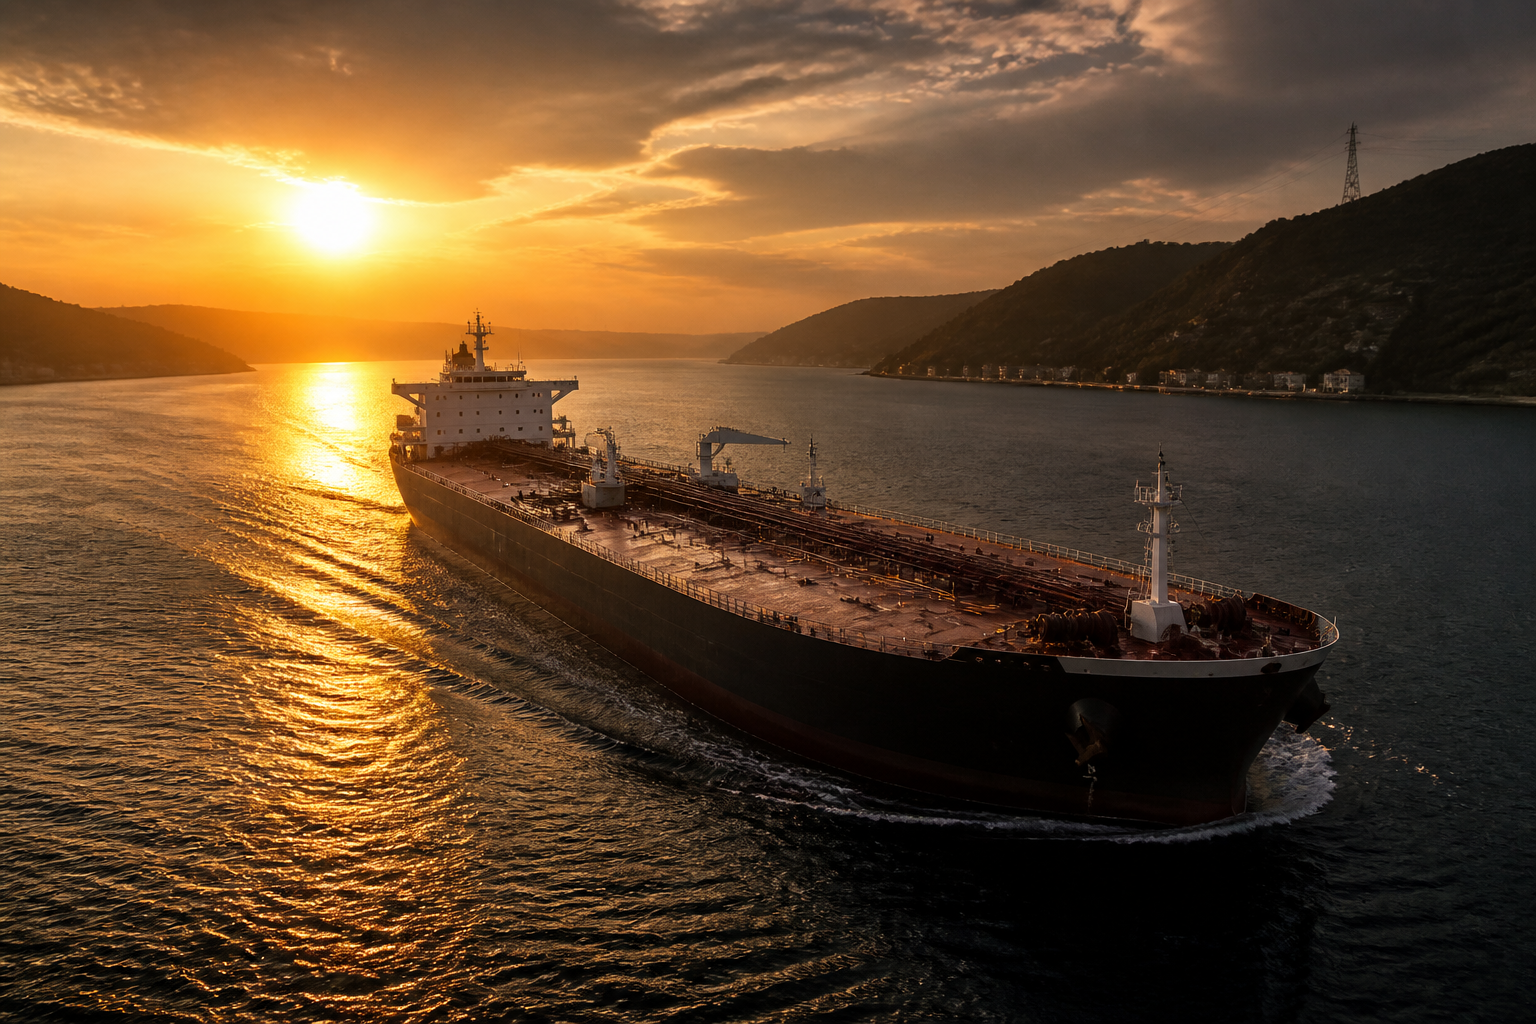
The enduring significance of the Strait of Hormuz as a global chokepoint has once again come into sharp focus, following a series of skirmishes involving United States and Iranian assets. This narrow waterway, through which approximately one-fifth of the world's daily oil consumption passes, remains the most sensitive barometer of global energy security. Any disruption here, whether through direct military intervention or the threat of increased insurance premiums for maritime transport, has an immediate and disproportionate impact on Brent and West Texas Intermediate benchmarks. Recent price jumps are a direct reflection of this insecurity, as market participants price in the possibility of a broader regional conflict that could stifle the flow of crude from the Persian Gulf to Asian and European refineries. For institutional investors, this recurring theatre of tension serves as a reminder that despite the rise of renewable infrastructure, the world’s economic machinery remains tethered to the stability of the Middle East.
Venezuelan Re-engagement and the Chevron Pivot
Parallel to the tensions in the Middle East is the evolving diplomatic landscape in Latin America, where the prospect of a deal between the United States and the Venezuelan government is creating significant ripples. Chevron, as a primary actor in this theatre, stands to benefit immensely from a relaxation of sanctions, a move that would allow for a controlled increase in heavy crude exports to American refineries. This potential rapprochement represents a pragmatic shift in foreign policy, prioritising energy price stability and domestic supply security over long-term isolationist strategies. The rise in Chevron’s stock value is not merely a reaction to current oil prices, but a bet on the company’s ability to unlock vast, under-utilised reserves in the Orinoco Belt. If successful, this re-integration of Venezuelan supply could provide a necessary cushion against supply shocks elsewhere, though it remains fraught with political risk and the challenges of rehabilitating a decaying state-owned infrastructure.
Market Resilience Amidst Broader Economic Uncertainty
Despite the broader headwinds facing the global economy, including persistent inflation and the specter of high interest rates, energy stocks have outperformed many other sectors in recent weeks. The NYSE Energy Sector Index has consistently trended upward, often diverging from the Dow Jones Industrial Average, which has faced periodic sell-offs. This divergence highlights the defensive qualities of the energy sector in an inflationary environment. Major players such as ExxonMobil, Halliburton, and Schlumberger continue to benefit from robust cash flows and a disciplined approach to capital expenditure. Unlike the previous decade’s obsession with production growth at all costs, the current corporate strategy is one of value extraction and shareholder returns. This newfound fiscal discipline, combined with elevated commodity prices, has transformed energy companies into attractive havens for capital that is fleeing more speculative corners of the market.
The Service Sector and the Efficiency Frontier
While the primary producers often capture the headlines, the performance of oilfield service giants like Halliburton and Schlumberger offers a more nuanced view of the industry’s health. These firms are increasingly focusing on technological integration and operational efficiency to maximise the output of existing wells. The demand for advanced seismic imaging, automated drilling platforms, and sustainable extraction techniques is rising as companies seek to lower their break-even costs. This technological arms race is particularly evident in the American Permian Basin, where efficiency gains have allowed production to remain steady even as the rig count fluctuates. For the service sector, the current environment is one of cautious optimism, as higher oil prices incentivise operators to invest in the maintenance and optimization of their asset portfolios, ensuring a steady stream of contracts for the foreseeable future.
Transition Risks and the Long Term Outlook for Fossil Capital
The current boom in traditional energy stocks exists in a state of cognitive dissonance with the global commitment to a net-zero future. While the immediate focus is on security of supply and price mitigation, the long-term structural decline of fossil fuel demand remains an inescapable reality. Major institutional investors are increasingly scrutinising the carbon intensity of their portfolios, putting pressure on firms like BP and Shell to accelerate their diversification into green hydrogen, offshore wind, and electric vehicle charging networks. The challenge for these giants is to manage a graceful exit from their legacy assets while simultaneously building the infrastructure of the future. The recent fluctuations in the energy sector illustrate a market that is trying to price in both the immediate scarcity of oil and the eventual obsolescence of the internal combustion engine, a balancing act that requires immense strategic foresight.
A Forecast of Volatile Equilibrium
Looking ahead, the energy market is likely to remain in a state of volatile equilibrium, where geopolitical shocks are periodically offset by technological gains and shifting diplomatic alliances. The interaction between OPEC policy, American shale production, and the emerging supply from South America will determine the price ceiling for the next eighteen months. Investors must prepare for a landscape where traditional supply-demand fundamentals are frequently interrupted by non-market events, such as the ongoing developments in the Strait of Hormuz or policy shifts in Washington and Caracas. While the energy sector currently offers lucrative returns and a hedge against inflation, the underlying instability of the global order suggests that these gains will be hard-won. The coming years will be defined by this tension between the world’s lingering dependence on old energy and the fitful, expensive, and necessary birth of the new energy economy.