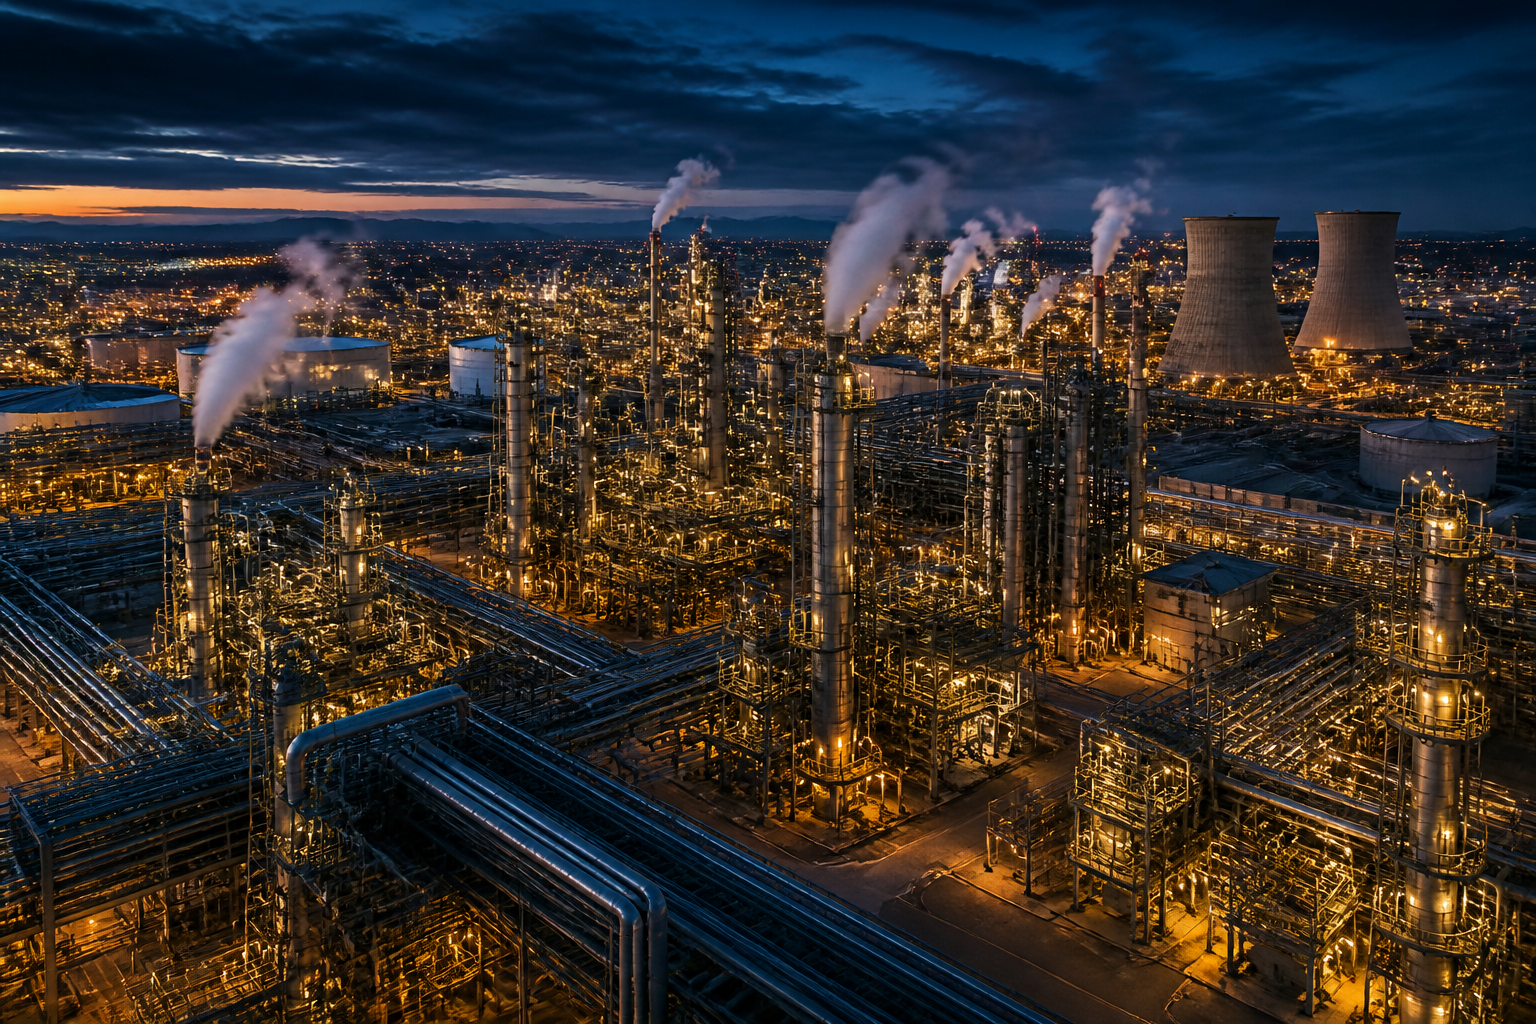
The Refined Paradox: Navigating Global Volatility and the Downstream Supply Crunch
Global energy markets face a divergence between crude stability and refined product volatility. From Japanese interest rate hikes to Venezuelan production tests, the downstream sector remains the primary driver of industrial inflation.
The global energy landscape is currently defined by a profound and unsettling divergence between the price of raw crude and the cost of the refined products that power the modern industrial economy. While upstream production levels from the Permian Basin to the North Sea have achieved a tenuous equilibrium, the downstream sector remains embroiled in a structural crisis that threatens to entrench inflationary pressures across the Group of Seven nations. The historical correlation between Brent crude benchmarks and the price of middle distillates has fractured, leaving policymakers at the Bank of Japan and the Federal Reserve to contend with a reality where energy security is no longer merely about extraction, but about the industrial capacity to transform. This disconnect is exacerbated by a tightening cycle in Japanese monetary policy, where recent interest rate hikes have begun to recalibrate the flow of capital into capital-intensive energy infrastructure, further complicating the long-term investment horizon for global refinery upgrades. As the global economy navigates this period of precarious transition, the resilience of corporate margins now depends less on the abundance of oil and more on the thinning margins of the crack spread.
The Widening Chasm of Downstream Capacity
The fundamental challenge facing the global energy sector is not a lack of geological reserves, but a chronic deficit in the sophisticated refining infrastructure required to meet modern environmental and industrial standards. Recent analysis by Deloitte indicates that prices for refined energy products, particularly diesel and jet fuel, have remained stubbornly elevated even as the price of West Texas Intermediate has moderated. This phenomenon is largely a consequence of decades of under-investment in the downstream sector within Western economies, where regulatory uncertainty and the overarching push toward decarbonisation have discouraged the construction of new refineries. The result is a brittle system where a single mechanical failure at a major facility, such as the ExxonMobil complex in Antwerp or the Reliance industries hub in Jamnagar, can trigger a disproportionate spike in regional fuel costs. This lack of a domestic refining buffer has forced many European and North American markets to become increasingly dependent on imports from the Middle East and East Asia, creating a fragile logistics chain that is highly sensitive to maritime disruptions and geopolitical theatre.
Monetary Tightening and the Japanese Influence
In a move that has sent ripples through the international financial markets, the Bank of Japan recently opted to raise interest rates, a decision that carries significant implications for energy financing. For decades, the availability of low-cost capital in Japan supported the expansion of energy trading houses and heavy industry across the Asia-Pacific region. As the cost of borrowing rises in Tokyo, the financing for massive infrastructure projects, including liquefied natural gas terminals and refinery modernisations, faces a new hurdle. This shift occurs at a time when Japanese retail sectors are already grappling with the dense, competitive pressures of a changing domestic economy, where pricing power is increasingly difficult to maintain. The intersection of higher interest rates and elevated energy costs is squeezing the margins of manufacturing giants from Toyota to Mitsubishi, forcing a reassessment of supply chain efficiency. If the yen continues to strengthen against the dollar, the cost of importing dollar-denominated energy commodities may decrease for Japan, yet the global cost of capital for energy development will likely remain on an upward trajectory, stifling the very investment needed to alleviate the refining bottleneck.
The Venezuelan Test and Geopolitical Realignments
South America has re-emerged as a critical theatre of energy uncertainty, with Venezuela serving as the primary focal point for market speculators and geopolitical strategists alike. The ongoing test of Venezuelan oil production capacity remains a wildcard in the global supply equation. Despite possessing some of the largest proven oil reserves on the planet, the state-owned Petroleos de Venezuela has struggled with crumbling infrastructure and the weight of international sanctions. Any significant re-entry of Venezuelan heavy crude into the global market would require billions of dollars in foreign direct investment and a stable political framework, neither of which appears imminent. However, the potential for Venezuelan output to act as a counterweight to OPEC plus production cuts remains a subject of intense debate in Washington and Brussels. The difficulty lies in the quality of the crude itself, as Venezuelan extra-heavy oil requires specialised refining processes that are currently in short supply, further reinforcing the argument that the world possesses plenty of oil but lacks the specific capacity to process it into usable fuel.
Southeast Asian Growth and Trade Imbalances
The economic indicators emerging from Malaysia provide a compelling snapshot of the broader shifts occurring within the emerging markets of Southeast Asia. Recent trade balance figures show a significant surplus, driven in large part by a robust expansion in exports. Malaysia, as a key player in both the electronics and petroleum sectors, has seen its consumer price index tick upward, reflecting the global trend of persistent energy-led inflation. The Malaysian trade data, showing imports and exports both climbing beyond market expectations, suggests a region that is rapidly industrialising and consuming energy at an accelerating rate. This internal demand within the Association of Southeast Asian Nations is competing directly with the export needs of the West, further tightening the global market for refined products. As Malaysia and its neighbours continue to build out their own downstream capabilities, the traditional flow of energy from the East to the West may be interrupted by the requirements of domestic growth, creating a new set of challenges for energy-importing nations in the Northern Hemisphere.
The Renewable Overcapacity Dilemma
While the focus remains on fossil fuels, the renewable energy sector is confronting a crisis of its own, characterised by massive overcapacity in the production of solar panels and wind turbine components. This glut, primarily driven by state-supported manufacturing in China, has led to a collapse in prices for renewable hardware, which, while beneficial for installers, has devastated the profit margins of Western manufacturers. The imbalance between the supply of green technology and the capacity of electrical grids to integrate it has created a bottleneck that mirrors the issues found in the oil refining sector. Without significant investment in grid stabilisation and battery storage, the oversupply of solar modules will fail to translate into a corresponding reduction in the demand for baseload power provided by natural gas and coal. This structural mismatch highlights the complexity of the energy transition, where the abundance of a primary resource, whether it be sunlight or crude oil, is rendered ineffective by the lack of intermediate infrastructure required to deliver that energy to the end-consumer.
Analytical Outlook for the Energy Transition
Looking ahead toward the final years of the decade, the energy sector is poised for a period of radical recalibration. The era of cheap, abundant energy has been replaced by a landscape defined by technical bottlenecks and geopolitical friction. Businesses must now operate under the assumption that high energy prices are not a temporary aberration but a permanent feature of the post-pandemic global order. The ability of a nation to secure its own refining capacity and grid resilience will become the primary metric of its economic sovereignty. We expect to see a surge in strategic partnerships between traditional energy companies and technology firms, as the integration of artificial intelligence into refinery operations offers the only viable path toward increasing efficiency without the multi-billion dollar cost of building new greenfield sites. The global economy is no longer just fighting for oil, it is fighting for the industrial intelligence to use it effectively. Investors should remain wary of the volatility in middle distillates, as the gap between crude and refined prices is unlikely to close until a massive, coordinated effort in downstream infrastructure is realised across both the developed and developing worlds.