The Fragile Furrow: Navigating Logistical Stasis and The New Agrarian Frontier
Global agriculture faces a dual crisis of logistical inertia in the United States and emerging structural shifts in West Africa. This editorial examines the impact of Mississippi water levels on trade and the rise of Taiwanese-backed innovation in emerging markets.
The global agricultural landscape is currently defined by a profound dichotomy between the structural inertia of established markets and the experimental vitality of emerging frontiers. While the United States Department of Agriculture (USDA) grapples with a domestic planting season marred by hydrological constraints and unseasonable climate rhythms, the global south is witnessing a quiet revolution of institutional investment and diplomatic partnership. The recent data provided by the National Agricultural Statistics Service (NASS) highlights a precarious start to the 2026 corn season, with plantings recorded at a mere four per cent as of mid-April. This lethargy is not merely a statistical anomaly but a symptom of a deeper malaise within the North American logistical spine. Simultaneously, nations such as Nigeria are pivoting toward a more robust model of post-harvest management and public-private synergy, suggesting that the center of gravity in agrifood innovation may be shifting toward those regions most desperate to solve the riddle of food sovereignty.
The Mississippi Constraint and the American Heartland
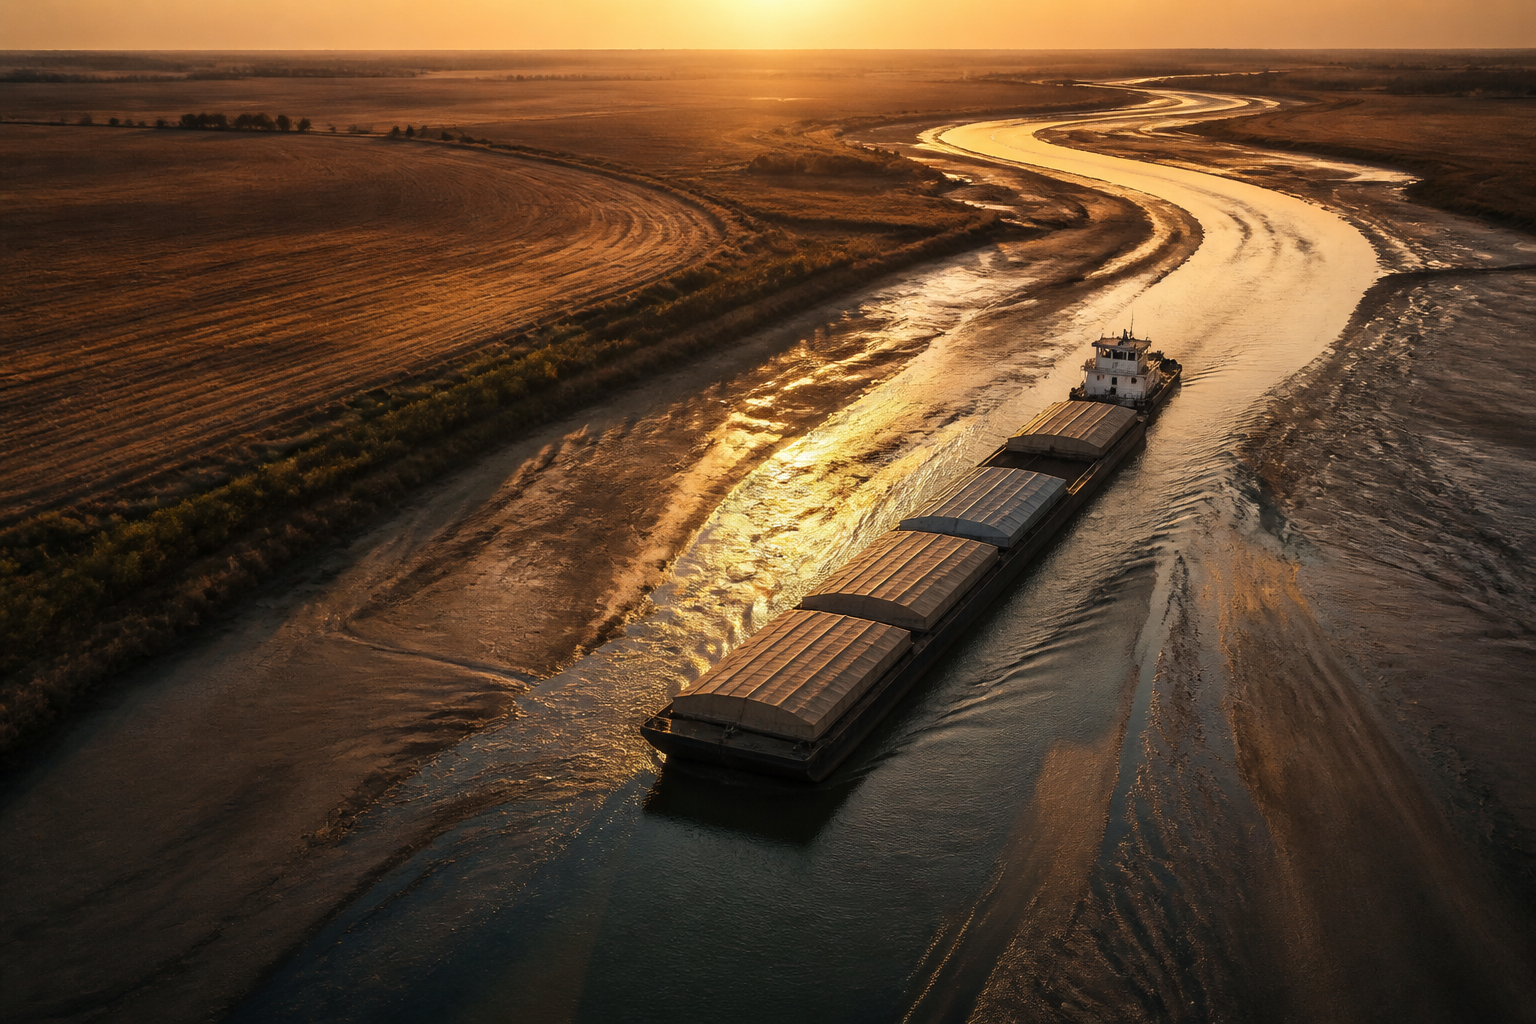
The American Midwest remains the primary engine of global caloric exports, yet its reliance on the Mississippi River system has become an Achilles’ heel. The latest intelligence from NASS and reports circulated by major industry observers suggest that the 2026 planting season is off to a stuttering start. Corn plantings, having risen from two per cent to four per cent in the week ending April 18th, reflect a cautious approach by producers who are increasingly wary of soil moisture volatility and the reliability of downstream transit. The challenge is twofold: the physical act of sowing is delayed by regional weather patterns, but the broader economic calculation is dampened by the ongoing struggle of the Mississippi River to maintain water levels conducive to heavy barge traffic. This waterway serves as the critical artery for grain exports leaving the Gulf of Mexico, and any disruption there creates a backlog that vibrates through the entire supply chain, depressing local prices at the silo while inflating global benchmarks.
Institutional analysts suggest that this persistent hydrological instability is no longer a seasonal outlier but a permanent fixture of the Midwestern operational environment. For firms like Archer-Daniels-Midland and Bunge, the logistical calculus is shifting from efficiency to resilience. The cost of transshipment by rail or lorry remains prohibitively expensive for bulk commodities when compared to river transit, yet the unpredictability of the river’s depth is forcing a re-evaluation of just-in-time delivery models. This structural bottleneck in the United States provides a stark contrast to the aggressive infrastructure development being seen elsewhere, forcing global buyers to consider whether the American breadbasket can maintain its historic reliability in a decade defined by climatic extremes.
West African Consolidation and the Nigerian Pivot
While the United States manages its internal logistical constraints, the West African agricultural sector is undergoing a period of intense policy evolution. In Nigeria, the discourse has moved beyond the mere increase of primary yields to the sophisticated management of the post-harvest lifecycle. The Bank of Agriculture Limited and various regional ministries have begun to formalise partnerships that aim to mitigate the chronic losses that have historically plagued the sector. Reports from the ground indicate a growing narrative of investment, where the focus is now squarely on the creation of integrated value chains that link smallholder farmers directly to industrial processors. This is not merely a philanthropic endeavour but a calculated economic strategy designed to insulate the Nigerian economy from the volatility of international commodity prices and the precariousness of foreign exchange reserves.
This shift is supported by a burgeoning ecosystem of agritech startups and government-backed initiatives that seek to digitise the marketplace. By providing farmers with real-time data on price discovery and weather patterns, and by improving the availability of temperature-controlled storage, Nigeria is attempting to transition from a subsistence-dominated model to one of commercial scale. The entry of stronger institutional partnerships suggests that the international investment community is beginning to view the Nigerian agrifood sector as a viable alternative to the traditional, and increasingly saturated, markets of the West. The success of this pivot will depend on the sustained commitment of the federal government to provide the necessary physical infrastructure, roads, electricity, and water, to support these nascent agricultural hubs.
Diplomatic Agronomy: The Taiwanese Influence in East Asia and Beyond
A particularly intriguing development in the realm of agricultural diplomacy is the deepening partnership between the Ministry of Agriculture, Food Security & New Growth Industries and the Embassy of the Republic of China (Taiwan). This collaboration represents a sophisticated form of soft power, where Taiwan exports its considerable expertise in high-value horticulture and biotechnology to partner nations. Recent completions of joint projects highlight a focus on precision agriculture and the introduction of resilient crop varieties that are better suited to the changing climates of the tropics. This is not a one-way transfer of knowledge but a strategic alignment that allows Taiwan to secure its own food supply chains while fostering goodwill and economic dependencies in strategically important regions.
These unique partnerships are often overlooked in the broader context of global grain trades, yet they represent the vanguard of agrifood innovation. Taiwan’s ability to maximize yields on limited arable land provides a blueprint for other nations facing similar constraints of geography and urbanisation. By investing in foreign agricultural sectors, Taiwan is creating a network of satellite production hubs that utilise its proprietary technology and seeds. For the recipient nations, these partnerships offer a shortcut to modernizing their agricultural base without the need for the decades of research and development that usually accompany such a transition. It is a model of globalised agriculture that prioritises technological integration over mere land mass, a trend that is likely to accelerate as arable land becomes a scarcer commodity.
Localised Innovation Grants and the Micro-Economy of Agribusiness
Turning our attention back to the North American context, there is a growing trend of hyper-localised investment aimed at fostering resilience within small to medium-sized agricultural enterprises. In Maryland, for instance, the Frederick County government recently announced the allocation of $150,185 in Agriculture Innovation Grants to six local businesses. While the sum may seem modest when compared to the multi-billion dollar subsidies of the Farm Bill, these targeted injections of capital are critical for the survival of the diversified farm. These grants are designed to help businesses expand their operations, integrate new technologies, and improve their market reach, demonstrating a bottom-up approach to agricultural stability.
This model of micro-funding suggests a recognition by local authorities that the future of agriculture may not lie solely in the vast monocultures of the plains, but in the ability of regional producers to serve local markets with high-value products. For the recipients in Frederick County and similar programmes in Prince George’s County, these funds provide the leverage needed to invest in equipment like robotic milkers, advanced irrigation systems, or on-site processing facilities. By reducing the reliance on long-distance supply chains, these local businesses are creating a more resilient food system that is less vulnerable to the logistical failures seen on the Mississippi. It is a decentralised strategy that complements the large-scale industrial model, providing a necessary buffer against global shocks.
The Digitisation of Agricultural Statistics and Market Transparency
The role of the USDA and the National Agricultural Statistics Service in maintaining market transparency cannot be overstated. In an era where information is as much a commodity as the grain itself, the timely release of planting reports and crop condition assessments provides the essential data required for global price discovery. The move toward more accessible digital platforms, including the use of social media and real-time data visualisations, reflects a broader shift toward democratising agricultural intelligence. This transparency is vital for preventing the kind of market panics that can occur when information is siloed or delayed, particularly during seasons as fraught with uncertainty as the current one.
However, the reliance on these statistics also creates a pressure point. When the USDA reports a mere four per cent planting progress, the markets respond instantaneously. The challenge for policymakers is to ensure that these statistics are not only accurate but also contextualised. For example, the delay in corn planting may be offset by improvements in seed technology that allow for a shorter growing season, or by the potential for increased soybean acreage if the corn window closes. The ability of the NASS to capture these nuances will be critical for investors who are looking beyond the immediate headlines to understand the long-term health of the global food system.
A Forecast of Diversification and Resilience
Looking ahead, the global agrifood sector is entering a period of significant realignment. The traditional dominance of the American heartland is being challenged not by a single rival, but by a combination of domestic logistical decay and the rise of innovative competitors in the global south and East Asia. The persistent challenges facing the Mississippi River system serve as a reminder that even the most established agricultural powers are not immune to the realities of climate change and infrastructure neglect. As a result, we expect to see a continued diversification of sourcing, with international buyers increasingly looking toward West Africa and South America to mitigate the risks associated with North American supply.
The future will also be defined by the continued integration of technology and diplomacy. The Taiwanese model of exporting agricultural expertise is likely to be emulated by other technologically advanced nations, creating a new form of 'agri-diplomacy' that reshapes global alliances. At the same time, the focus on post-harvest management and value-chain integration in markets like Nigeria will create new opportunities for private equity and institutional investors who are willing to navigate the complexities of emerging markets. The overarching theme is one of transition: from a world of predictable surpluses to one of managed scarcity, where the premium is placed on resilience, local innovation, and the mastery of the entire agricultural lifecycle. The nations and firms that succeed will be those that recognise that the furrow is no longer just a place to plant a seed, but a complex intersection of climate, logistics, and geopolitical strategy.