The Logistics Bottleneck: Global Distribution Amidst Rising Tensions and Costs
As transportation costs reach multi-year highs and central banks shift their stances, the global distribution sector faces a period of intense structural reform. Economic & Actu examines the forces reshaping the supply chain.
The global commerce landscape is currently navigating a period of profound transition, defined by a persistent upward trajectory in transportation costs that defies historical seasonal patterns. As we approach the final quarter of 2026, the resilience of international distribution networks is being tested by a confluence of rising freight rates, significant shifts in monetary policy from the Bank of Japan, and a fundamental realignment of China’s role within the global economic order. Data from the Bureau of Economic Analysis and recent market reports suggest that the cost of transporting virtually all categories of goods has reached levels not seen in several years, driven by factors far more complex than simple fuel price fluctuations. The institutional consensus suggests that the era of inexpensive logistics has yielded to a new reality of high-cost, high-friction trade, where the efficiency of the just-in-time model is increasingly subordinated to the imperatives of regional security and cost containment.
The Persistent Rise of Freight and Carriage Costs
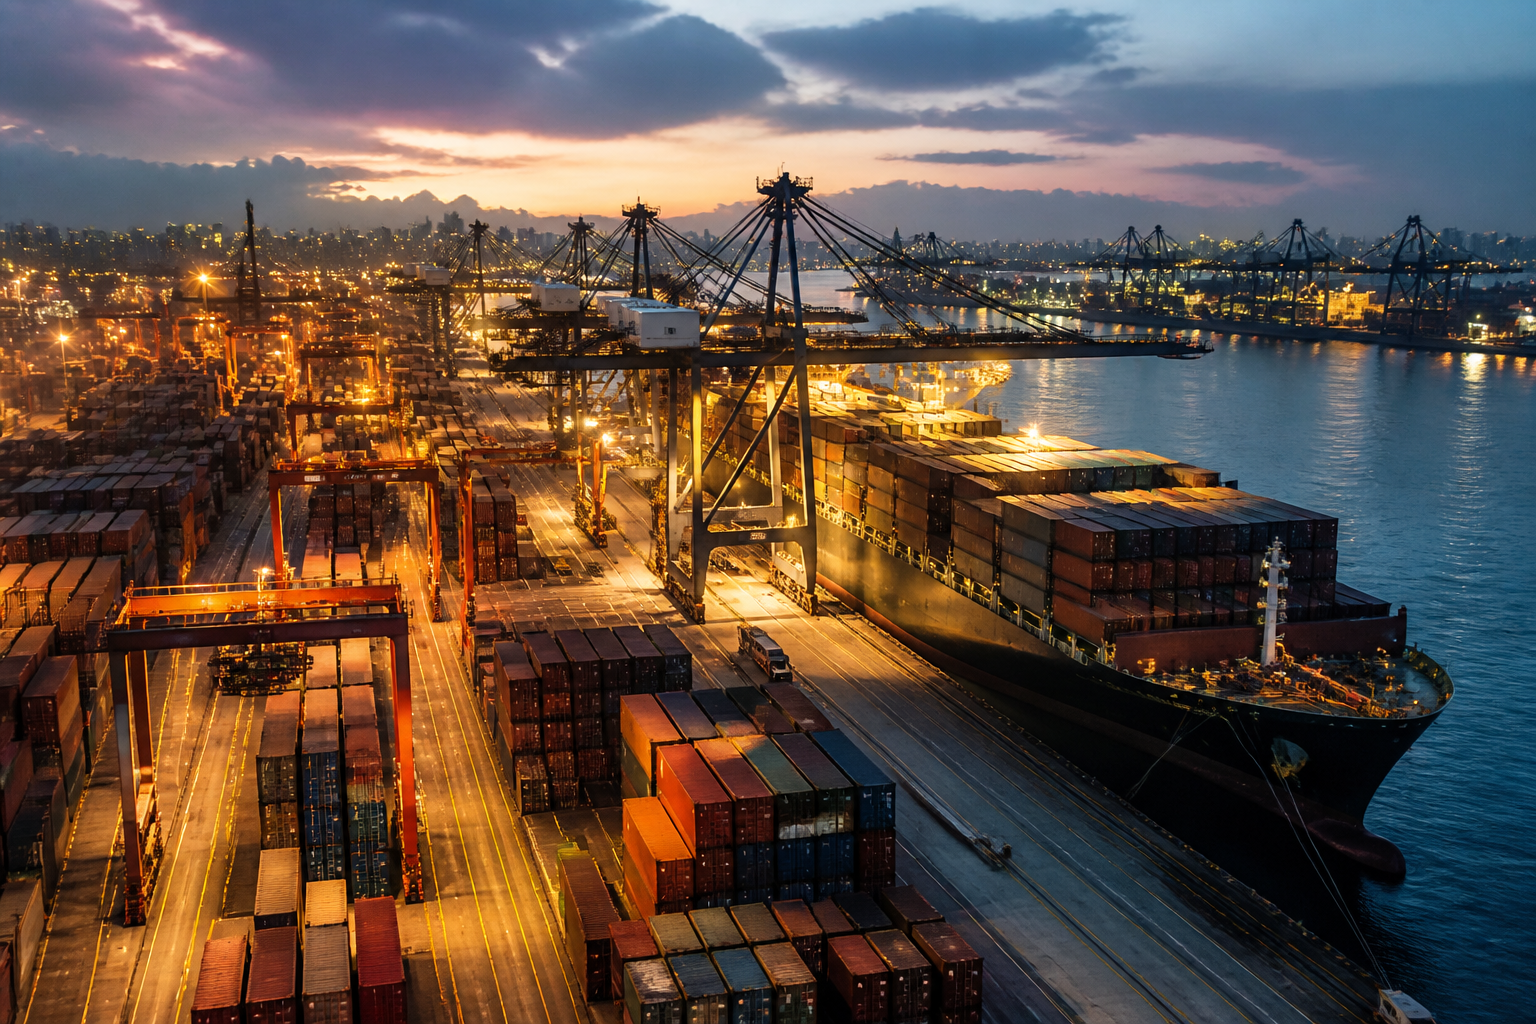
The current inflationary pressures within the distribution sector are particularly acute in the trucking and maritime shipping industries, where rates have surged despite relatively stable diesel prices. According to recent reports from the Wall Street Journal, the overheads associated with port operations and long-distance haulage have increased to a degree that is now being passed directly to the consumer, complicating the efforts of central banks to anchor inflation expectations. The increase is not merely a reflection of energy costs, but rather a symptom of structural deficiencies in port infrastructure and a chronic shortage of qualified operators across North America and Western Europe. Firms are finding that the premium for reliability has increased, as the unpredictability of global shipping routes necessitates larger capital reserves and more robust insurance coverage, all of which contribute to a higher baseline for the cost of goods sold.
Monetary Tightening and the Japanese Influence
External pressure on the global distribution framework is being exacerbated by a significant shift in Japanese monetary policy. The Bank of Japan has recently moved to tighten its stance, a decision that has sent ripples through international capital markets and affected the financing of large-scale logistics projects. As the yen strengthens and the cost of borrowing in Tokyo rises, the carry trades that once supported global liquidity are being unwound, leading to a more restrictive environment for industrial expansion. For distribution giants and international shipping conglomerates, this shift represents a departure from the low-interest environment that facilitated the massive vessel acquisitions and warehouse expansions of the past decade. The tightening in Japan, coupled with the ongoing vigilance of the United States Federal Reserve, suggests that the capital-intensive nature of the distribution sector will face higher hurdles in the coming fiscal years.
China and the New Paradigm of Global Trade
China’s evolving position in the world economy remains the primary variable in the distribution equation. As Beijing pivots towards a model of self-reliance and domestic consumption, the traditional flow of low-cost manufactured goods is undergoing a qualitative shift. Deloitte Insights recently highlighted that China is no longer merely the world’s factory, but is instead becoming a sophisticated exporter of high-value technology and green energy solutions. This transition requires a different kind of logistics infrastructure, one that prioritises the movement of high-tech components and precision machinery over bulk consumer commodities. Furthermore, the geopolitical friction between Beijing and Washington has prompted a diversification of supply chains, with many European and American firms seeking to reduce their dependency on Chinese ports by investing in alternative hubs across South-East Asia and Mexico.
Infrastructure Strains and the North American Response
In North America, the focus has shifted towards the domestic resilience of distribution networks. Events such as the Distribution and Logistics Week in Texas highlight the growing importance of regional hubs in sustaining economic growth. The Bureau of Economic Analysis has recently updated its measures of economic well-being and growth to include a more nuanced view of how logistics and infrastructure contribute to the overall Gross Domestic Product. These figures reveal that the bottlenecks in the American heartland are as significant as those at the coastal ports. The lack of modern, automated warehousing facilities and the decaying state of arterial road networks have created a situation where the final mile of delivery is often the most expensive and least efficient part of the journey. Institutional investment is now being directed towards the digitisation of these networks, yet the physical constraints of geography and labor remain formidable obstacles.
The Digital Imperative in Modern Commerce
To counter the rising costs of physical distribution, many firms are turning to advanced predictive analytics and blockchain-based tracking systems to optimise their inventories. The objective is to reduce the amount of time that capital is tied up in transit, a goal that has become critical as interest rates remain elevated. By employing sophisticated algorithms to forecast demand, distributors can position inventory closer to the end consumer, thereby mitigating the impact of high long-haul freight rates. However, this digital transformation is not a panacea. The integration of these technologies requires significant upfront expenditure and a workforce capable of managing complex data environments. Moreover, the increased reliance on digital systems introduces new vulnerabilities, as cyber-attacks on critical logistics infrastructure have become a prominent concern for national security agencies and corporate boards alike.
A Forecast for the Future of Distribution
Looking ahead to 2027, the outlook for the commerce and distribution sector is one of guarded pragmatism. The inflationary pressures currently bedevilling the industry are unlikely to dissipate quickly, as the structural causes of high freight rates and labor shortages require long-term systemic solutions rather than short-term policy fixes. We anticipate a period of consolidation, where larger distribution firms with the capital to invest in automation will gain market share at the expense of smaller, less efficient operators. The role of the state will also become more pronounced, as governments increasingly view the integrity of the supply chain as a matter of national interest. While the global economy will continue to trade, the days of seamless, frictionless, and inexpensive distribution are behind us, replaced by a more fragmented and costly landscape that demands greater strategic foresight from all participants in the international market.