The Resilience Of Global Value Chains Amidst A Realigned Monetary Landscape
An analytical exploration of how shifting interest rates in Japan and the United States, coupled with China's evolving industrial strategy, are reshaping international distribution networks and corporate logistics.
The global commerce and distribution landscape is currently navigating a period of profound structural realignment, driven by a rare synchronisation of shifting monetary policy and evolving geopolitical imperatives. While the Federal Reserve in the United States continues to calibrate its stance in response to cooling inflation and steady employment figures, the Bank of Japan has taken the decisive step of tightening its long-standing accommodative policy. This divergence has sent ripples through international credit markets, directly affecting the capital expenditure plans of multinational logistics firms and the inventory strategies of retail giants. The equilibrium that once defined the post-pandemic recovery has been replaced by a more complex, multi-polar reality where the cost of borrowing and the stability of currency exchange rates dictate the flow of goods across the Pacific and beyond. As we approach the final months of 2026, the resilience of these networks is being tested not just by the cost of capital, but by the necessity of building redundancy into supply chains that were previously optimised solely for efficiency.
The Monetary Rebalancing And Its Industrial Impact
The recent decision by the Bank of Japan to tighten its monetary policy marks a significant departure from decades of yield curve control and negative interest rates. For the commerce and distribution sector, this shift is far from academic. Japan remains a critical node in the global high-technology and automotive supply chains, and a stronger Yen, coupled with higher domestic borrowing costs, alters the internal economics of Japanese exporters. Major industrial players, including the likes of Toyota and various semiconductor equipment manufacturers, must now navigate a domestic environment where the cost of financing new production facilities is no longer negligible. This coincides with a period of intense scrutiny on the United States Federal Reserve, where officials such as John Williams are closely watched for signals regarding the future trajectory of American interest rates. The Bureau of Economic Analysis recently released data indicating that while the American consumer remains resilient, the pace of growth in personal consumption expenditures is moderating. This suggests that the distribution sector in North America may soon face a period of lower volume growth, forcing firms to focus on margin preservation through operational automation rather than pure expansion.
China And The Evolving Dynamics Of Global Logistics
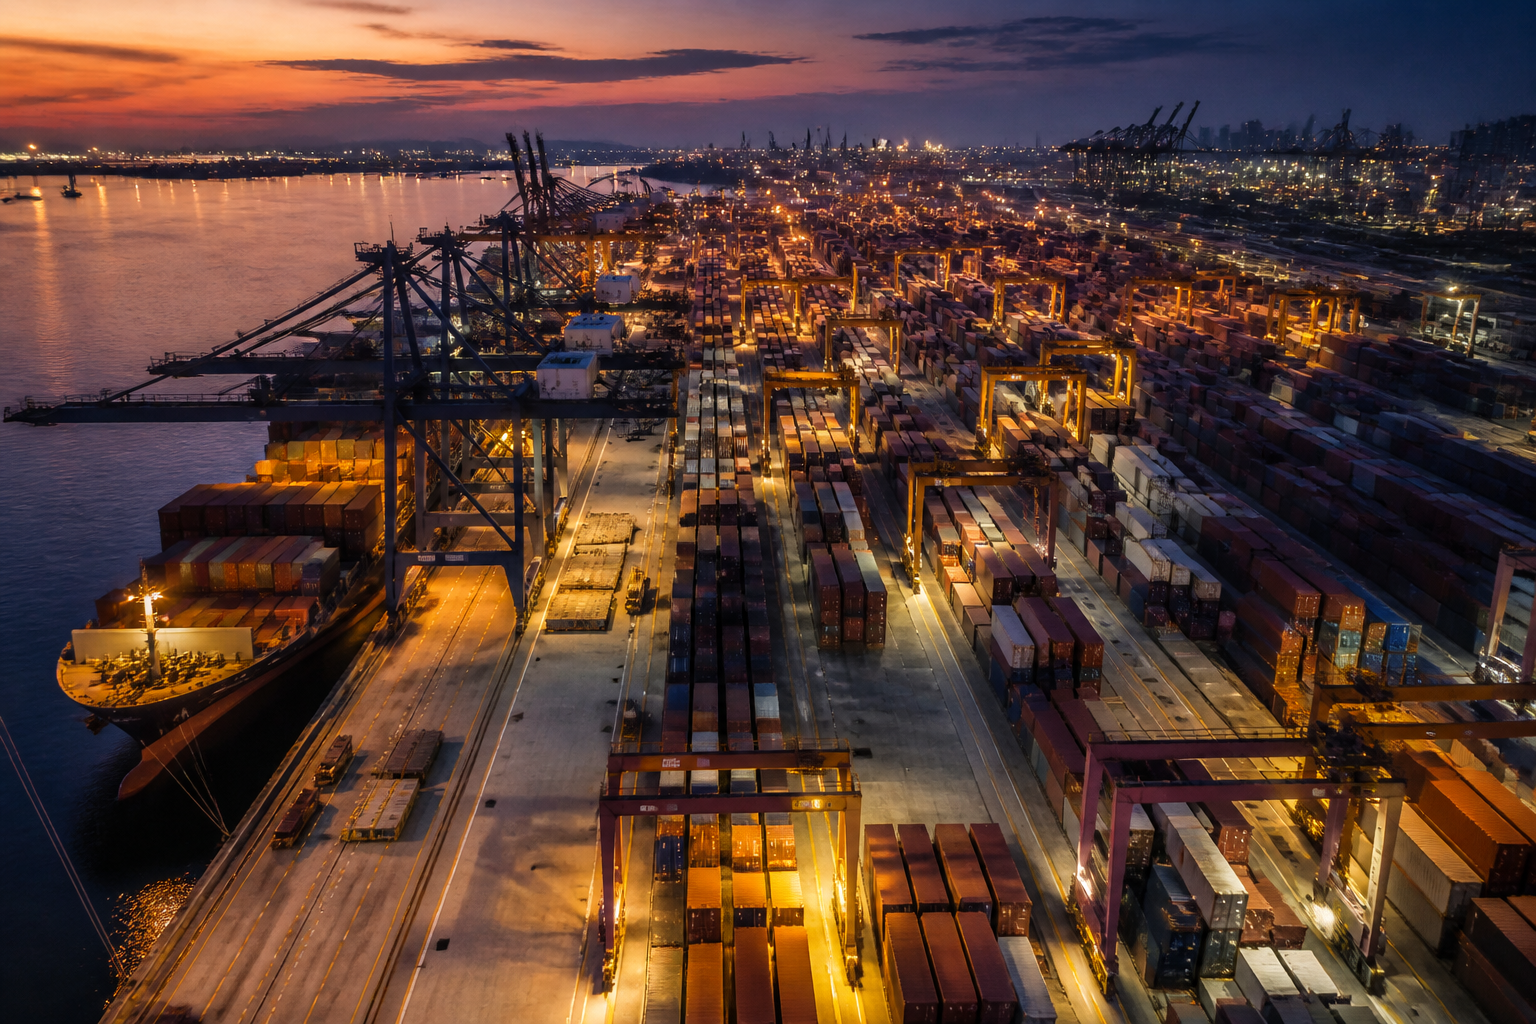
China is no longer merely the factory of the world, it is rapidly becoming a sophisticated coordinator of regional trade blocs. According to recent intelligence from Deloitte Insights, the Chinese role in the global economy is evolving from a low-cost manufacturing hub into a leader in green technology and digital commerce infrastructure. This transition has significant implications for the distribution sector, as Chinese firms like Alibaba and JD.com expand their physical footprints across Southeast Asia and Europe. The focus has shifted from shipping finished goods to the West to creating integrated logistics ecosystems that facilitate intra-Asian trade. However, this expansion occurs against a backdrop of increasing trade barriers and the trend of friend-shoring. European and American distributors are increasingly looking to diversify their sourcing away from a single-country dependency, leading to a surge in investment in logistics hubs in Vietnam, India, and Mexico. The challenge for these firms is that the infrastructure in these emerging hubs often lacks the maturity and scale of the Chinese ports, leading to short-term inefficiencies and increased landed costs for consumer products.
The Crisis In Industrial Services And Capital Goods
The distribution of industrial services and capital goods is facing its own set of unique headwinds, exemplified by the recent financial volatility surrounding major players like Bilfinger. The firm recently saw its shares decline by twenty percent following a lowered outlook and the announcement of significant job cuts. This serves as a cautionary tale for the broader sector, indicating that the demand for industrial maintenance and engineering services is highly sensitive to the broader economic climate. When major manufacturers face uncertainty, they often delay the very service contracts and equipment upgrades that firms like Bilfinger provide. This contraction in the industrial services market is a leading indicator of a broader slowdown in manufacturing investment. For distributors of heavy machinery and components, the current environment necessitates a pivot toward more flexible service-based models, such as equipment-as-a-service, which allow clients to avoid large upfront capital expenditures in favour of operational costs. This shift requires a fundamental restructuring of the balance sheet for many distribution firms, as they take on more asset risk in exchange for long-term contract stability.
Technological Integration And The Efficiency Frontier
In the face of rising labour costs and unpredictable energy prices, the commerce and distribution sector is doubling down on technological integration. The use of generative artificial intelligence and advanced robotics is no longer a luxury but a strategic necessity. Large-scale distributors are deploying autonomous mobile robots in warehouses to mitigate the impact of labour shortages, which remain a persistent issue in both Western Europe and North America. Beyond the warehouse floor, the application of predictive analytics is transforming inventory management. By leveraging real-time data from the Bureau of Economic Analysis on consumer spending patterns and regional employment trends, distributors can now position stock closer to the point of demand, thereby reducing the last-mile delivery costs that typically account for a significant portion of total logistics expenditure. The integration of blockchain technology for transparent tracking of goods through customs and international shipping routes is also gaining traction, providing the visibility needed to navigate the increasingly complex regulatory requirements of modern trade.
The Geopolitical Risk To Maritime And Surface Freight
Maritime trade, the lifeblood of global commerce, remains vulnerable to geopolitical instability and environmental pressures. The ongoing disruptions in major shipping lanes, coupled with the need for the shipping industry to meet stringent new carbon emission targets, have led to a sustained period of high freight rates. Major carriers are currently investing billions in dual-fuel vessels, but the transition to a carbon-neutral fleet is a multi-decade project that will require significant capital. On land, the transport sector is facing a similar transition. The recent market talk surrounding the automotive and transport sectors highlights the pressure on logistics firms to electrify their medium-duty and heavy-duty fleets. However, the lack of a robust charging infrastructure for heavy vehicles remains a significant bottleneck. Distributors are forced to balance the demands of environmental, social, and governance mandates with the hard realities of operational feasibility and cost. The winners in this space will be those who can secure long-term partnerships with energy providers and government agencies to build out the necessary infrastructure to support a decarbonised supply chain.
Strategic Outlook For The Coming Quarter
Looking ahead toward 2027, the commerce and distribution sector will likely be defined by a cautious optimism tempered by the realities of a higher-for-longer interest rate environment in many regions. The divergence in monetary policy between the East and the West will continue to create opportunities for currency arbitrage in trade financing, but it will also introduce new risks for firms with significant unhedged exposure. We expect to see a further consolidation in the logistics and distribution industry, as smaller players who cannot afford the necessary investments in automation and green technology are acquired by larger, more capital-rich competitors. The focus for executive leadership must remain on building agility into the supply chain. This means moving away from just-in-time models toward a just-in-case approach that prioritises resilience and reliability over absolute cost minimisation. While the road ahead is fraught with geopolitical and economic uncertainties, the fundamental importance of the distribution sector to the functioning of the global economy remains undiminished. Firms that can successfully marry technological innovation with prudent financial management will be well-positioned to navigate the complexities of this new era of global commerce.