The Infinite Frontier of Synthetic Intelligence and Regional Specialisation in Global Tech
This editorial examines the surge in artificial intelligence valuations, the rise of sovereign tech ecosystems, and the strategic pivot toward hardware integration as illustrated by firms like Halter and River AI.
The global technology sector is currently undergoing a structural transformation that defies traditional market cycles, characterized by an unprecedented concentration of capital within the artificial intelligence domain. While broader macroeconomic indicators suggest a period of cautious recalibration, the venture capital environment for synthetic intelligence continues to expand at a rate that challenges historical precedent. Recent weeks have witnessed valuations that would have appeared fanciful a mere decade ago, such as the thirteen billion dollar assessment of Lovable following a four hundred million dollar injection. This influx of liquidity is not merely a speculative bubble, rather, it represents a fundamental bet on the total reconfiguration of the digital economy. The sheer velocity of these investments, exemplified by the one billion dollar funding of River AI just two months after its inception, indicates that investors are no longer seeking incremental improvements, they are chasing the foundations of a new industrial paradigm. As these figures escalate, the narrative of innovation is shifting from simple software applications toward a more complex integration of compute power, proprietary datasets, and physical automation.
The Sovereign Tech Ecosystem and Regional Dominance
One of the most striking developments in the current landscape is the emergence of concentrated regional hubs that operate as sovereign technological ecosystems. A notable example is a specific nation of ten million inhabitants that has successfully fostered more than two thousand startups dedicated exclusively to artificial intelligence. This density of innovation suggests that geographical proximity and specialized talent pools remain critical, even in an era of distributed work. These hubs act as crucibles for breakthrough technologies, ranging from deep-learning algorithms to sophisticated robotics. By concentrating resources within a defined regulatory and cultural framework, these regions are creating a blueprint for how mid-sized nations can compete with traditional superpowers. The success of these ecosystems is built upon a synergy between government policy, academic excellence, and a risk-tolerant financial sector. This regionalization of tech leadership implies that the next phase of global competition will be defined not just by corporate prowess, but by the ability of specific territories to maintain a high density of specialized intellectual property.
The Convergence of Physical Automation and Digital Intelligence
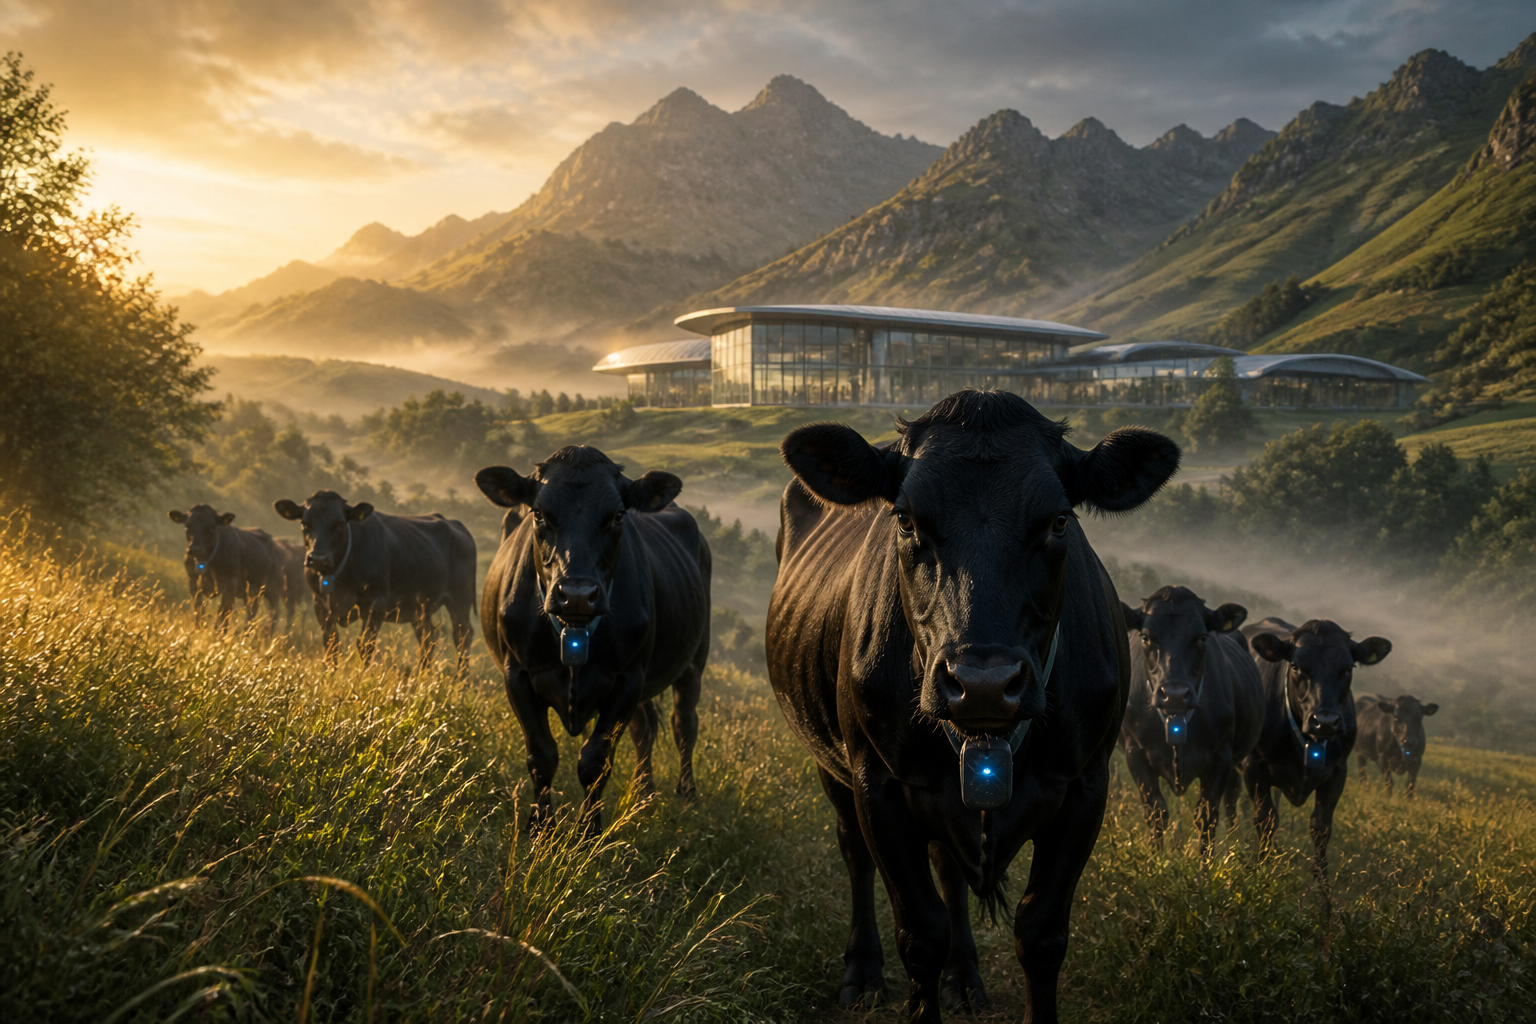
As the software layer of artificial intelligence matures, a secondary frontier is opening in the realm of physical automation. The work of firms like Halter, led by Craig Piggott, illustrates a significant pivot toward applying complex algorithms to tangible industries such as agriculture. By developing cattle collars that utilize virtual fencing technology, Halter demonstrates how the internet of things and intelligent software can fundamentally alter traditional land management. This integration of hardware and software represents a maturation of the tech sector, moving beyond the screen to interact directly with the physical environment. Farmers are now able to manage vast herds with a level of precision that was previously impossible, reducing labor costs and improving animal welfare. This trend toward the industrialization of AI suggests that the most resilient startups of the coming decade will be those that can bridge the gap between abstract code and real-world application. The success of such ventures highlights a growing investor appetite for technologies that provide immediate, measurable efficiencies in primary industries.
Consolidation and the Strategic Acquisition of Infrastructure
In the upper echelons of the tech industry, a trend toward consolidation is becoming increasingly apparent as major players seek to secure their supply chains and technological advantages. The ongoing discussions regarding Anthropic and its potential acquisition of Decart point to a strategic necessity for self-sufficiency in the AI stack. As large language models become more resource-intensive, the ability to control the underlying infrastructure, from chips to data centers, becomes a primary competitive advantage. This move toward vertical integration is a response to the scarcity of high-performance computing resources and the need for proprietary optimization. By acquiring specialized firms like Decart, major AI developers can insulate themselves from the volatility of the external hardware market. This consolidation also signals a shift in the startup lifecycle, where the most promising early-stage companies are rapidly absorbed into larger ecosystems before they can reach public markets. The result is a landscape dominated by a few massive entities that possess the capital to sustain the exorbitant costs of frontier research.
Capital Concentration and the Risk of Valuation Inflation
While the headline figures for recent funding rounds are impressive, they raise significant questions about the long-term sustainability of current valuation models. The lead taken by General Catalyst in the massive round for River AI serves as a testament to the aggressive posture of top-tier venture firms. However, when a two-month-old entity commands a billion-dollar valuation, the margin for error becomes razor-thin. This concentration of capital at the earliest stages of development creates a high-pressure environment where startups must achieve scale at an unnatural pace. The risk is that the focus shifts from sustainable product development to the maintenance of investor confidence and the justification of enormous paper wealth. Furthermore, as Microsoft and other tech giants continue to invest billions into projects like Stargate, the barrier to entry for independent startups becomes increasingly formidable. The industry must navigate the tension between the genuine revolutionary potential of these technologies and the financial froth that inevitably accompanies such rapid shifts in market sentiment.
The Evolving Role of Large Scale Institutional Investment
Institutional investors are increasingly viewing artificial intelligence not as a sub-sector of technology, but as a foundational utility comparable to electricity or the internet itself. This shift in perception is driving investments that reach into the billions, such as the proposed three billion dollar commitment to the Stargate initiative. Such massive deployments of capital are necessary to build the physical infrastructure required to support the next generation of synthetic intelligence. This involves the construction of hyperscale data centers and the securing of vast amounts of renewable energy to power them. The involvement of global investment firms and major corporations suggests a belief that the returns on AI will be captured by those who control the physical and digital architecture of the system. Consequently, the distinction between a tech company and an infrastructure provider is blurring, as the physical requirements of modern computing demand a level of capital expenditure that was once reserved for national utility projects. This evolution indicates that the future of innovation will be as much about logistics and energy management as it is about software engineering.
A Strategic Outlook for the New Digital Economy
Looking toward the conclusion of this decade, the trajectory of the innovation sector appears to be defined by a paradox of consolidation and diversification. On one hand, the immense capital requirements of frontier AI models will likely lead to a market dominated by a small number of extraordinarily well-funded entities. On the other hand, the application of these models to specialized niches, such as the agricultural technology pioneered by Halter, will create a vibrant ecosystem of smaller firms that provide high-value solutions in specific verticals. The primary challenge for policymakers and investors alike will be to ensure that the concentration of power at the infrastructure level does not stifle the creative potential of the regional hubs that have proven so fertile for new ideas. As regional ecosystems continue to mature, they will likely become the primary sources of practical, applied innovation, while the major global players focus on the development of foundational intelligence. The resilience of the global economy will depend on the successful integration of these two layers, creating a technological landscape that is both broad in its application and robust in its foundation. The coming years will reveal whether the current rush of capital into AI will yield a sustainable new era of productivity or if the industry must eventually confront a period of significant rationalization.