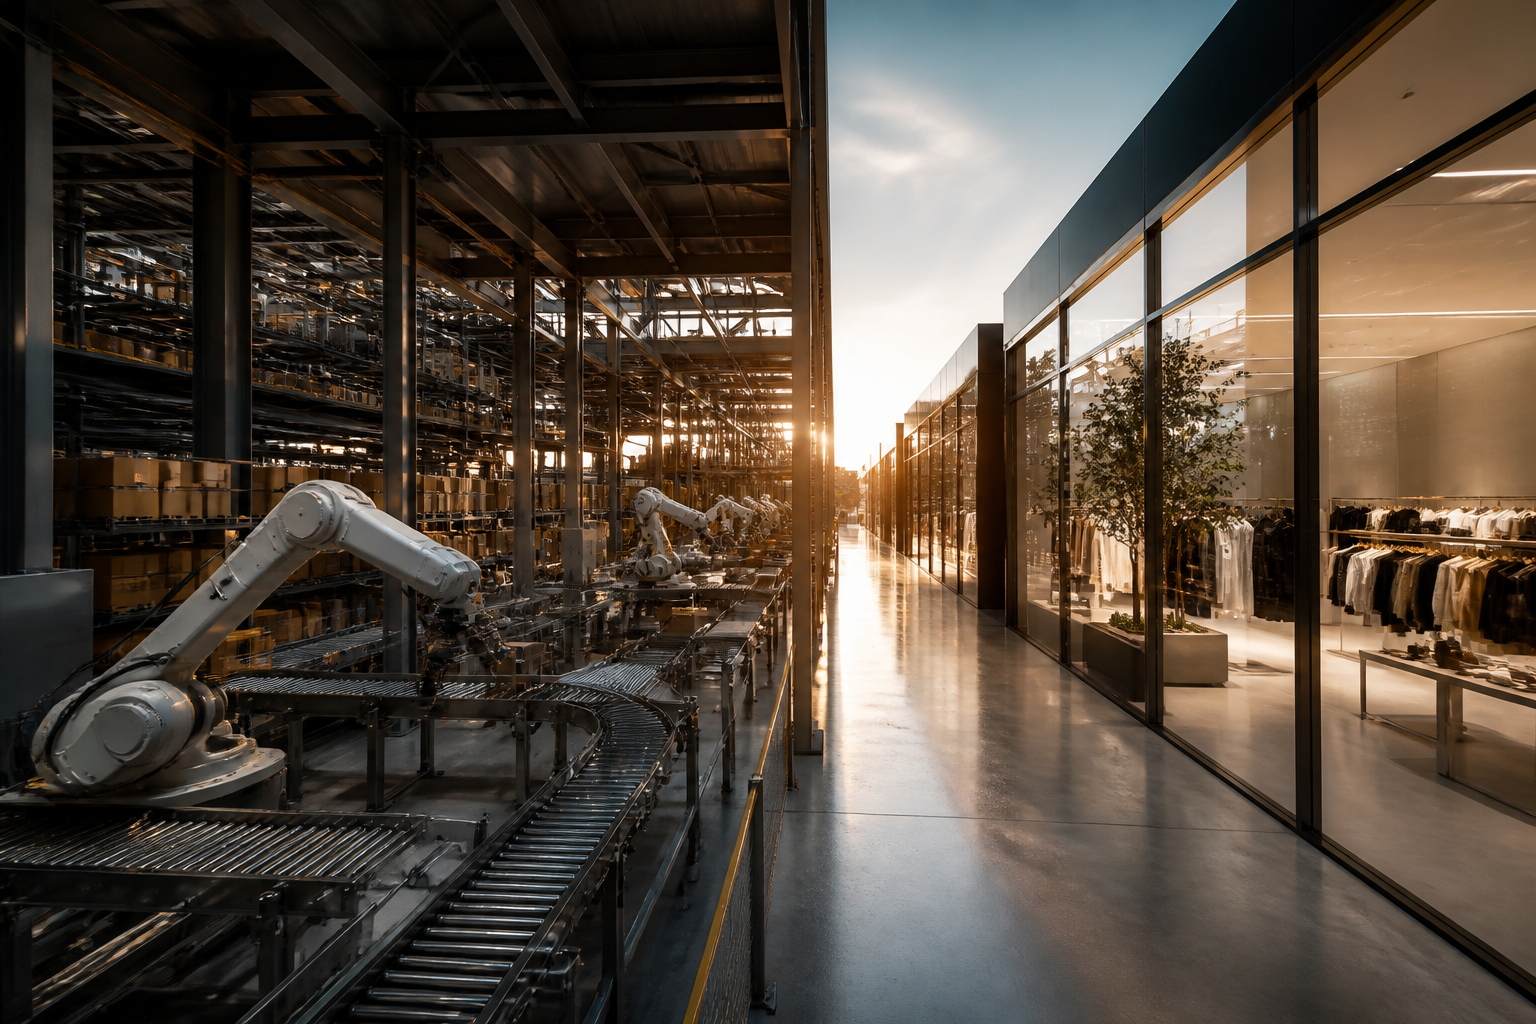
The Post-Digital Equilibrium: Reconfiguring The Global Commerce Landscape
An analytical exploration into the convergence of brick-and-mortar resilience and advanced digital logistics. This editorial examines how global retailers are navigating the shift from pure-play digital growth to integrated omnichannel stability.
The global commerce landscape is currently undergoing a structural realignment that challenges the long-held assumption that digital platforms would eventually render physical storefronts obsolete. In the wake of the pandemic-induced surge in online consumption, a more nuanced equilibrium is emerging, one where the distinction between e-commerce and traditional retail has become largely academic. As institutional investors scrutinise the quarterly performance of industry bellwethers such as Amazon, Walmart, and the LVMH group, it has become evident that the most resilient entities are those which have successfully synthesised digital agility with the logistical permanence of physical assets. This transformation is not merely a tactical shift, but a fundamental re-engineering of the retail value chain, necessitating a departure from the growth-at-all-costs mentality that defined the previous decade. The current macroeconomic environment, characterised by persistent inflationary pressures and a tightening of consumer discretionary spend, serves as a rigorous testing ground for these new integrated models.
The Resurgence of the Physical Anchor
Contrary to the dire predictions of a retail apocalypse that dominated headlines in the mid-twenty-tens, the physical store has re-emerged as a critical component of the modern distribution network. Major retailers in the United States and Western Europe are increasingly viewing their brick-and-mortar locations not merely as points of sale, but as distributed micro-fulfilment centres that reduce the prohibitive costs associated with the last-mile delivery. The investment strategies of firms like Target and Nordstrom reflect this shift, as they repurpose floor space to facilitate buy-online-pick-up-in-store services, which significantly enhance inventory turnover and customer retention. By leveraging existing physical footprints, these companies can mitigate the rising logistics costs that have plagued pure-play e-commerce ventures. Furthermore, the physical environment provides a sensory engagement that digital interfaces cannot replicate, serving as a vital touchpoint for brand storytelling and experiential marketing in an increasingly crowded marketplace.
Algorithmic Precision and Inventory Optimisation
While physical assets provide the foundation, the intelligence layer of modern commerce is being redefined by sophisticated data analytics and machine learning. Retailers are now employing predictive algorithms to anticipate local demand with unprecedented accuracy, allowing for the pre-positioning of stock closer to the end consumer. This level of logistical foresight is essential in a climate where supply chain disruptions remain a persistent threat to profitability. The use of artificial intelligence extends beyond inventory management into the realm of dynamic pricing and hyper-personalised marketing, where companies like Alibaba and JD dot com have set high benchmarks in the Asian markets. These technological advancements enable a more efficient allocation of capital, reducing the volume of unsold inventory that has historically weighed down the balance sheets of global apparel and consumer electronics firms. The integration of these tools into the daily operations of traditional retailers represents a significant barrier to entry for smaller competitors who lack the scale to invest in proprietary technology stacks.
The Geopolitics of Distribution and Supply Resilience
The geographic concentration of manufacturing and the fragility of global shipping routes have forced a re-evaluation of distribution strategies on a systemic level. The recent volatility in the Red Sea and the ongoing trade tensions between the United States and China have accelerated a trend towards near-shoring and friend-shoring. European retailers are increasingly looking to Turkey, North Africa, and Eastern Europe to diversify their sourcing, thereby reducing lead times and exposure to trans-pacific logistical bottlenecks. This shift is particularly evident in the fast-fashion sector, where the ability to respond to shifting trends in real time is the primary driver of competitive advantage. Companies that have over-indexed on low-cost manufacturing in distant geographies now find themselves at a disadvantage compared to those with more localized and flexible supply chains. The drive for resilience is also prompting significant investment in automated warehousing and robotics, as firms seek to insulate themselves from labour shortages and rising wage demands in their domestic markets.
Consumer Psychology and the Value Proposition
As the cost-of-living crisis persists across many developed economies, the psychology of the consumer has shifted towards a more calculated and value-oriented approach. This has led to a bifurcation in the market, where luxury brands continue to exhibit pricing power while mid-market retailers struggle to maintain margins. The success of discount formats and private-label offerings indicates a pragmatic turn in consumer behaviour, where brand loyalty is frequently secondary to perceived utility and price. Retailers must now navigate a landscape where transparency is absolute, as mobile technology allows consumers to compare prices and read reviews instantaneously. To counter this, successful firms are focusing on enhancing the total value proposition, incorporating sustainability credentials, ethical sourcing, and superior post-purchase support into their core offering. The rise of the circular economy, manifested in the growth of resale and rental platforms, further complicates the traditional model of linear consumption and requires a flexible approach to asset management.
The Financial Imperative of Unified Commerce
From a capital markets perspective, the valuation metrics for commerce and distribution firms are evolving to reflect the importance of integrated operations. Investors are moving away from simple metrics such as gross merchandise volume in favour of more robust indicators of long-term health, including customer acquisition cost to lifetime value ratios and contribution margins. The consolidation of the industry is likely to continue as larger players with strong balance sheets acquire innovative startups that offer niche technological capabilities or access to new demographic segments. The recent performance of retail stocks on the S&P 500 and the FTSE 100 suggests that the market is rewarding companies that demonstrate a clear path to profitability through operational efficiency rather than speculative expansion. The ability to manage complex omnichannel returns, which remains one of the greatest drains on retail profitability, has become a key differentiator for institutional investors seeking stability in a volatile sector.
Future Horizons and the Synthesis of Technology
Looking toward the end of the decade, the convergence of physical and digital commerce will likely reach its zenith through the adoption of spatial computing and augmented reality. These technologies will allow consumers to visualise products in their own environments with high fidelity, further bridging the gap between the convenience of digital browsing and the certainty of physical inspection. However, the success of these innovations will depend on the underlying infrastructure of commerce, specifically the robustness of data privacy frameworks and the seamlessness of cross-border payment systems. As the digital and physical realms continue to merge, the retailers that thrive will be those that view technology not as an end in itself, but as a means to facilitate a more human-centric and efficient exchange of value. The era of pure digital disruption is concluding, giving way to an era of structural sophistication where operational excellence and strategic foresight are the primary currencies of success. The winners in this new epoch will be defined by their ability to maintain agility at scale, ensuring they remain relevant to a consumer base that is increasingly discerning, technologically empowered, and environmentally conscious.