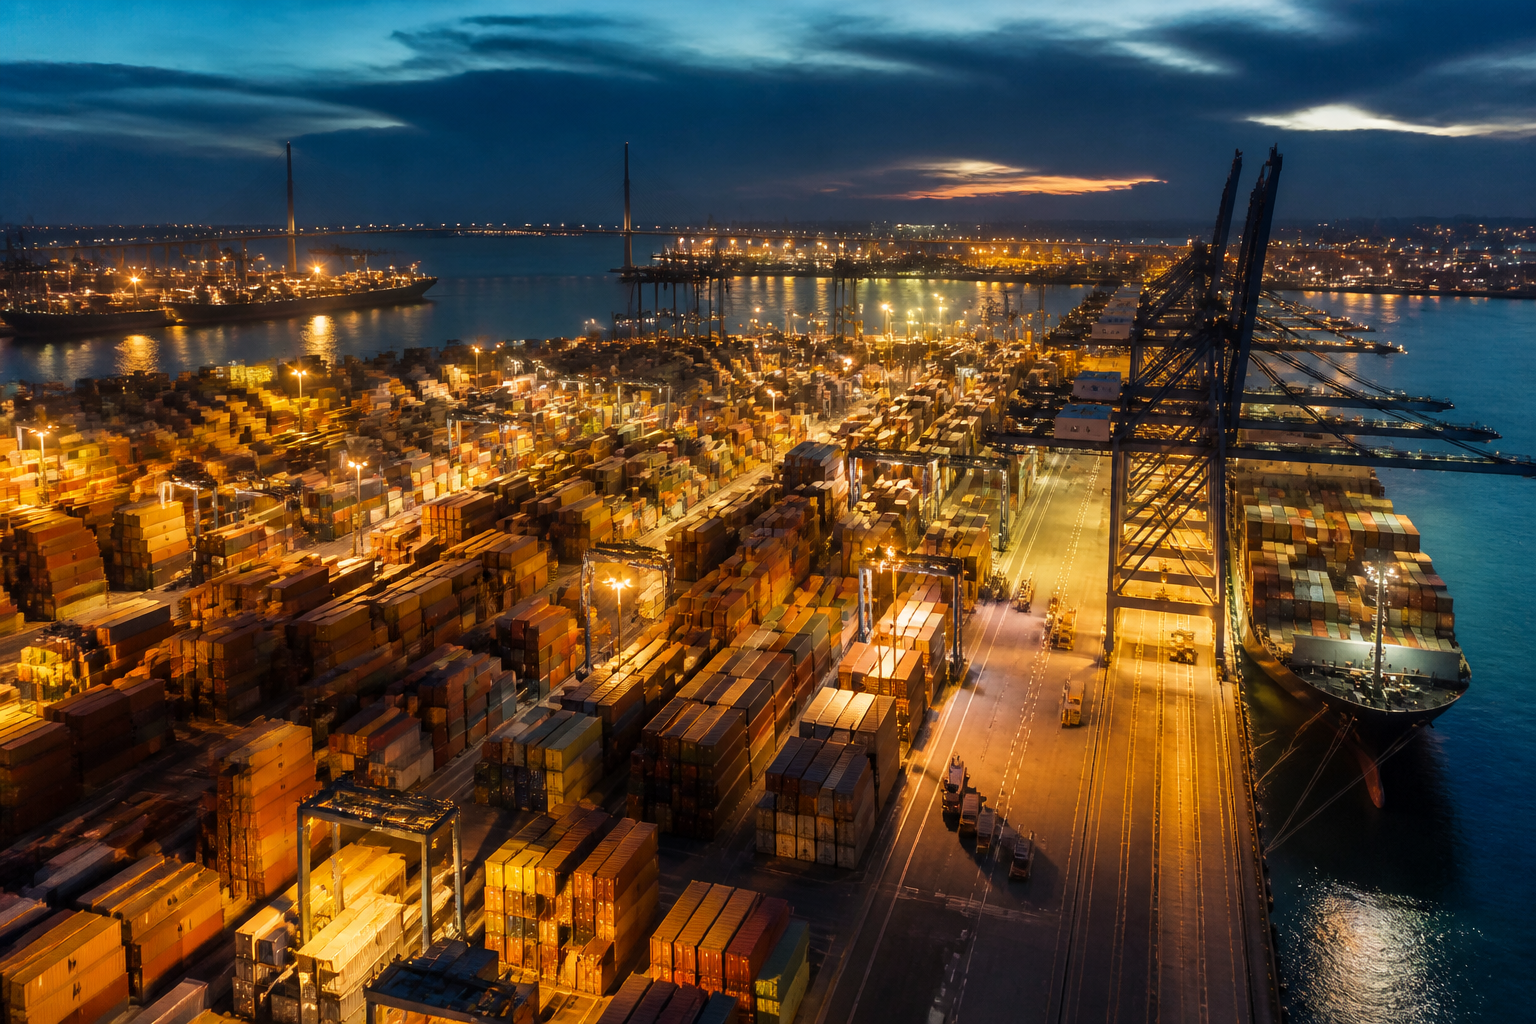
The Fragile Recovery: Commerce and Distribution in a Protectionist Era
A deep analysis of the fracturing global supply chain, the slowdown in North American retail spending, and the multibillion-pound investments in artificial intelligence that are redefining the future of commerce.
The global commerce landscape is currently navigating a period of profound transition, characterized by a cooling of consumer enthusiasm in the West and a simultaneous acceleration of technological investment. Recent data from the United States Census Bureau suggests that the robust spending patterns which sustained post-pandemic growth are finally succumbing to the cumulative pressures of inflation and eroded purchasing power. This softening of retail demand arrives at an awkward juncture for international distributors who are already grappling with a resurgence of protectionist sentiment. From the looming trade tensions between the United States and Canada to the staggering capital expenditure required for artificial intelligence infrastructure, the traditional playbooks of global trade are being systematically rewritten. The industry now finds itself at the intersection of a cyclical downturn and a structural revolution, requiring a delicate balance between fiscal prudence and the necessity of technological adoption.
The Cooling of the North American Consumer
For much of the past two years, the American consumer has acted as the primary engine of global economic resilience, defying expectations of a slowdown. However, recent indicators from July and August suggest that this period of exceptionalism may be reaching its conclusion. Monthly retail sales figures have begun to exhibit a downward trajectory, following a significant deceleration in growth during the preceding quarter. This retreat is not merely a statistical anomaly but a reflection of a broader shift in household sentiment. As families across the United States exhaust their pandemic-era savings and face the reality of sustained high interest rates, the propensity to spend on discretionary goods has diminished. This trend is particularly evident in the electronics and home furnishing sectors, where high-ticket items are being deferred in favour of essential expenditure. For global distributors, this pivot necessitates a rapid recalibration of inventory levels and a shift in focus toward value-driven propositions as the era of easy consumption draws to a close.
Trade Frictions and the End of Frictionless Commerce
The logistical efficiency that once defined global commerce is being challenged by a renewed emphasis on economic nationalism. A significant flashpoint has emerged on the North American continent, where the United States and Canada appear to be spiralling toward a comprehensive trade war. The announcement of post-labour day tariffs by the Canadian government signals a departure from the collaborative spirit of the USMCA agreement. These measures, often targeted at sensitive industries such as steel and aluminium, threaten to introduce new costs into the distribution network. When the world's largest trading partners engage in such tit-for-tat exchanges, the ripples are felt throughout the entire supply chain. Importers must now contend with unpredictable duty costs, which are inevitably passed on to the consumer, further dampening demand. This geopolitical friction is forcing a re-evaluation of just-in-time manufacturing, as firms increasingly look toward near-shoring or friend-shoring to mitigate the risks associated with volatile trade policies.
The Artificial Intelligence Arms Race in Distribution
While traditional retail metrics may be under pressure, the investment in the underlying technology of commerce shows no sign of abating. Companies like Amazon are currently engaged in a massive effort to overhaul their operational models for the age of artificial intelligence. Under the leadership of Andy Jassy, the retail giant is moving beyond simple automation toward a more integrated, AI-driven approach to logistics and customer engagement. This is not merely an incremental improvement but a fundamental redesign of how goods are predicted, stored, and delivered. The goal is to create a self-healing supply chain that can anticipate shifts in consumer behaviour before they manifest in sales data. However, the capital requirements for such a transformation are astronomical. This creates a widening chasm between the technological incumbents and smaller players who lack the balance sheet strength to compete in a world where data processing power is as critical as physical warehouse space.
Infrastructure and the Bayou Data Boom
The physical manifestation of this digital shift is most visible in the massive construction projects currently underway across the American South. Meta has committed to a two hundred billion dollar data centre project in Louisiana, a scale of investment that rivals the traditional industrial projects of the previous century. This facility, situated in the Bayou, represents a strategic bet on the future of generative AI and its application in commerce. Such projects are transforming local economies and placing immense pressure on regional power grids. For the distribution sector, these data centres are the new ports and railways of the twenty-first century. They provide the computational capacity necessary to manage global inventories in real-time and to personalise the digital shopping experience for millions of users. The environmental and social implications of these energy-intensive hubs are only beginning to be understood, yet they remain essential for any firm hoping to maintain a competitive edge in the modern economy.
Global Economic Headwinds and Market Trends
Beyond the North American sphere, the global economic outlook remains clouded by uncertainty. The BL Morning Report and other market indicators suggest that emerging markets are equally vulnerable to the fluctuations in Western demand. In regions like Southeast Asia and the Indian subcontinent, the growth of the middle class provides a potential offset to cooling Western markets, but this is contingent on the stability of global trade flows. The Hindu Business Line notes that market trends in August have been particularly sensitive to news regarding central bank policies and interest rate projections. As the Federal Reserve and the Bank of England contemplate the timing of potential rate cuts, the distribution sector remains in a state of suspended animation. High borrowing costs continue to stifle investment in new warehouse facilities and shipping fleets, while also making it more expensive for consumers to finance large purchases. The result is a period of stagnation where firms are forced to prioritise efficiency and cost-cutting over expansion.
The Resurgence of Strategic Assets and Energy Security
A surprising element of the current landscape is the return of legacy industrial sites to the forefront of the economic conversation. The revival of America's most infamous nuclear sites and other mothballed energy projects reflects a growing recognition that the digital economy requires a reliable and massive supply of carbon-free power. Without a stable energy foundation, the ambitious plans of tech firms to revolutionise commerce will remain unfulfilled. This intersection of energy policy and commercial strategy is becoming increasingly tight. Logistics providers are now looking toward green energy solutions not only for their delivery fleets but also to power the massive automated sorting centres that form the backbone of modern distribution. The move toward sustainability is no longer just a matter of corporate social responsibility but is becoming a core operational requirement in a world where energy security is inextricably linked to economic performance.
Forward Outlook: Navigating the New Normal
As we look toward the final quarter of the year and into the next, the path for commerce and distribution appears fraught with both peril and opportunity. The immediate challenge will be navigating the softening demand in major economies without resorting to destructive price wars. Firms must leverage the advancements in AI to optimize their margins and reduce waste, ensuring that every unit in the supply chain is accounted for with precision. The broader geopolitical environment remains the greatest wildcard, as the trend toward protectionism shows no signs of reversing. Success in this new era will be defined by agility and the ability to operate across fragmented markets. Those who can integrate advanced technology with a resilient, diversified supply chain will be best positioned to thrive. While the era of frictionless global trade may be over, the era of intelligent, adaptive commerce is only just beginning, and it will require a level of strategic sophistication that far exceeds anything seen in the previous decade.